The Price of a Freddo as an Economic Indicator
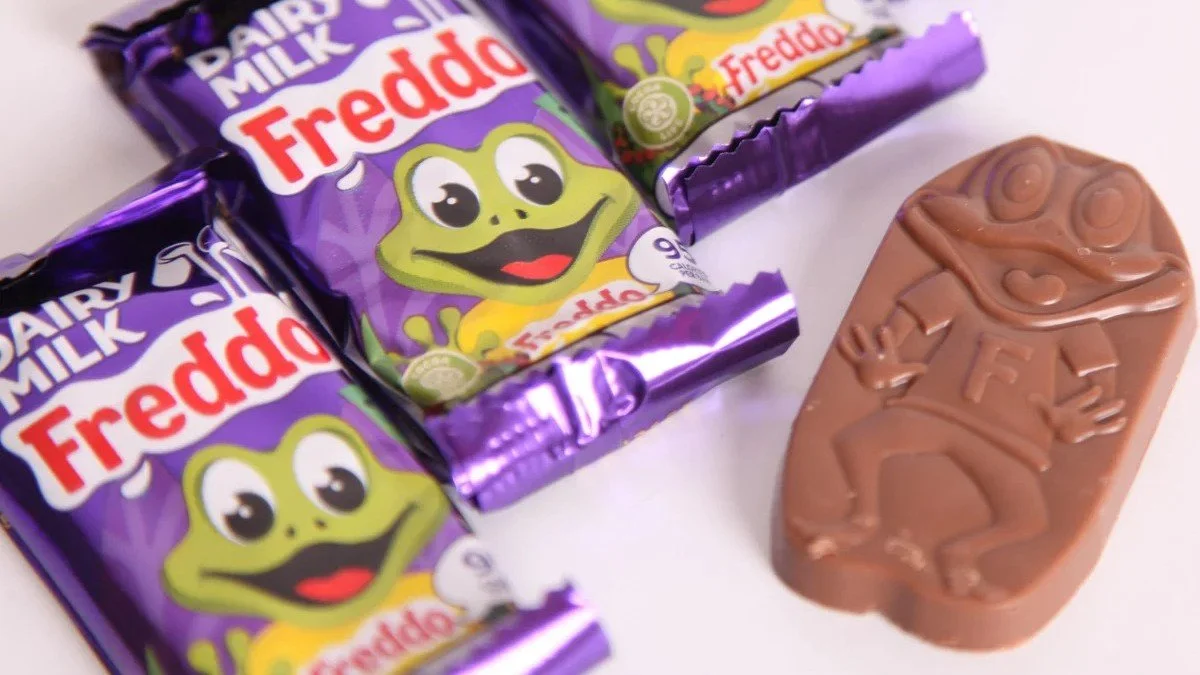
Before we start, let me explain to those readers outside of the UK, the significance of a Dairy Milk Freddo chocolate bar and its relevance to this post. The “Freddo” is an 18g (0.63 oz) chocolate bar, in the shape of an anthropomorphic frog. When it was re-launched by Cadbury in 1990 (it had previously been manufactured by an Australian confectionery company in the seventies), it was priced at 10p (£0.10). It remained at that price until 2005 when a 1p to 2p increase began to occur each year. By 2016 Freddos were retailing at 25p. However, the following year the price “lept” to 30p with an increase that was double its usual yearly rise. This led to public outrage across social media. Since then the price of a Freddo has waxed and waned. Tesco supermarket reduced the price back to 10p as part of their centenary celebrations. The post COVID price in 2022 hit 49p. At present, the average price of a Freddo in the UK is somewhere around 35p.
Before we start, let me explain to those readers outside of the UK, the significance of a Dairy Milk Freddo chocolate bar and its relevance to this post. The “Freddo” is an 18g (0.63 oz) chocolate bar, in the shape of an anthropomorphic frog. When it was re-launched by Cadbury in 1990 (it had previously been manufactured by an Australian confectionery company in the seventies), it was priced at 10p (£0.10). It remained at that price until 2005 when a 1p to 2p increase began to occur each year. By 2016 Freddos were retailing at 25p. However, the following year the price “lept” to 30p with an increase that was double its usual yearly rise. This led to public outrage across social media. Since then the price of a Freddo has waxed and waned. Tesco supermarket reduced the price back to 10p as part of their centenary celebrations. The post COVID price in 2022 hit 49p. At present, the average price of a Freddo in the UK is somewhere around 35p.
Although to the layman the price of a Dairy Milk Freddo chocolate bar may seem somewhat trivial, it has started to appear as some sort of economic indicator in the tabloid press and in mainstream political discourse. This was further compounded in October 2024, Labour MP Patrick Hurley launched a campaign to reduce the price of the Freddo as a way to engage young people in politics and discussions about the cost of living crisis. Although it was as somewhat light-hearted statement, the use of a Freddo as an accessible frame of reference, does have some merit. It is easily defined and quantified, as well as being very easily recognised. However, does such a consumer item serve any real use in economic discourse? Funnily enough, the answer is actually, “yes”, although it is mainly as an illustration of inflation, rather than a genuine economic indicator.
The Freddo works unusually well in public discussion because it is familiar, inexpensive and easily remembered. Many people recall it costing about 10p during the 1990s and early 2000s, whereas it now commonly costs roughly 30–35p, although individual retailers may charge considerably more. That makes the cumulative effect of rising prices immediately comprehensible in a way that an abstract index number often is not. A Freddo can be used as a small case study for the following:
Price inflation: How the nominal price of a fixed product rises over time.
Shrinkflation: Whether the weight or quantity changes as well as the price.
Price stickiness: Inexpensive products often remain at one conspicuous price for years, then rise in relatively large steps rather than moving smoothly.
Supply chains and costs: Chocolate involves cocoa, milk, sugar, energy, packaging, transport, labour and retail margins.
Consumer psychology: People notice frequent and familiar purchases more than many larger but less frequent expenses.
That last point is economically important. Bank of England research has found that food prices have a disproportionately strong influence on British households’ perceptions and expectations of inflation. Other research similarly indicates that consumers tend to form their inflation expectations partly from the grocery prices they personally encounter. A memorable item such as a Freddo can therefore tell us something about how inflation is perceived and discussed, even when it tells us little about the true overall inflation rate.
However, the Freddo is just one branded product, made by one company and sold by retailers with different pricing strategies. Its price may change because of promotions, profit margins, packaging decisions, brand positioning or a manufacturer’s desire to maintain a convenient price point. Indeed, analysis of its production costs suggests that fluctuations in the cocoa price alone account for only a limited portion of what shoppers pay. The Freddo also represents a negligible portion of normal household expenditure. Official inflation figures instead track a large, weighted collection of representative goods and services. The Office for National Statistic’s 2026 CPI basket contains 760 representative items, with their influence determined by how much households collectively spend on each of the relevant categories. Housing, transport, energy and services consequently matter far more than a small chocolate bar.
Overall, the Freddo is best regarded as a cultural cost-of-living index, rather than a more significant economic indicator. It is a good indicator of how inflation feels, a useful teaching device for explaining cumulative price rises and an interesting microeconomic example. That being said, it is not a sufficient instrument for measuring the overall state of the British economy and its complexities, which is why the Chancellor of the Exchequer does not feature them in their fiscal policies or end of year budget analysis. Used light-heartedly, it makes economic discussion more accessible. Used as evidence that official inflation is inaccurate, or as a substitute for CPI, wage growth, household costs or purchasing power, it becomes misleading. The distinction is essentially one between economic storytelling and economic measurement. But it does makes for a fun blog post. What is the equivalent of a Freddo in your country?
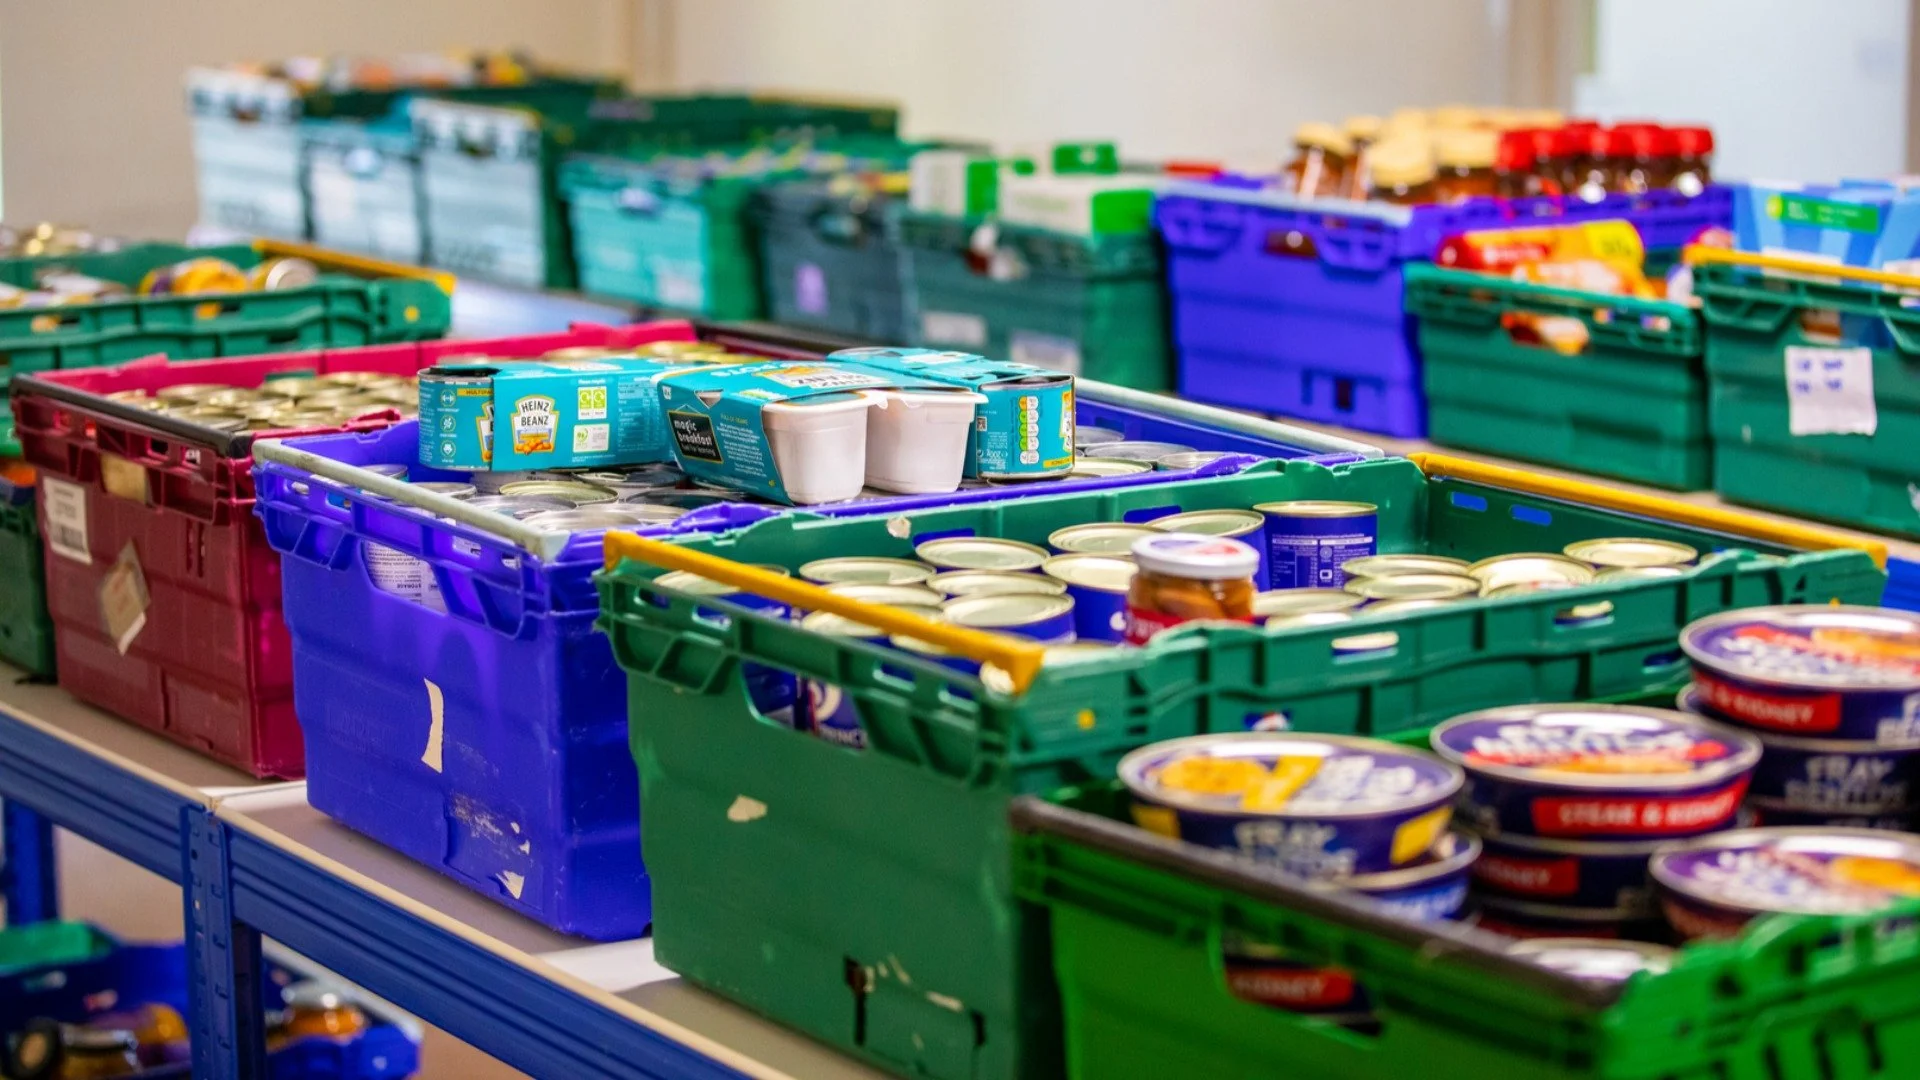
Every Thursday, Mrs P volunteers at a food bank that is run from a local church; Avery Hill Christian Fellowship. Today there was a shortage of staff so I agreed to help out. It proved to be an equitable arrangement as she collated the various orders and I packed the bags and took them to the respective clients. The food bank itself is organised and administered by the Trussell Trust, a UK based NGO and charity providing emergency food and support to people locked in poverty. It is open for 2 to 3 hours a week depending upon demand. During today’s session we served just six people. Some weeks its can be triple that amount. Upon closure, a member of staff from the Trussel Trust did a stock take and collated a list of what was needed. This is provided by various local church communities via parishioners donations, as well as local supermarkets who have an arrangement with the trust to provide surplus stock or good approaching the end of their sales window.
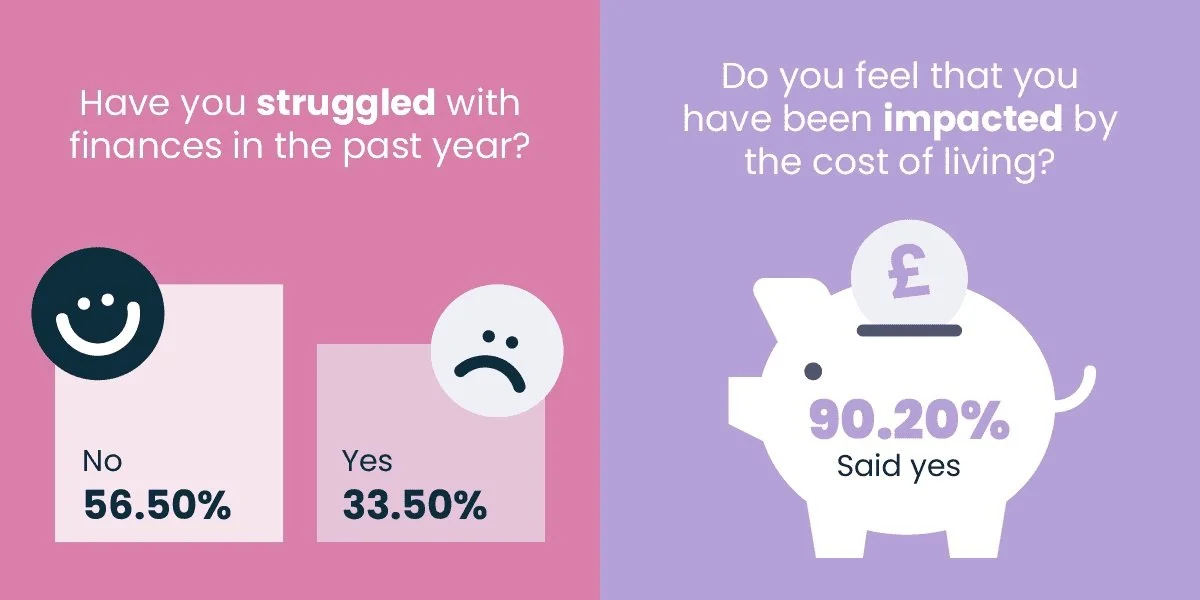
Our household is currently trying to reduce our monthly overheads in response to the ever increasing cost of living. April is not that far away and a great many service providers will increase their rates and tariff as the new financial year begins. Then there is the ongoing effects, both direct and indirect, of inflation to consider. Although the UK inflation rate is dropping, currently sitting at 3.4% in December 2025, food inflation remains higher at 4.5%. Being based in the UK, salaries and billed services tend to be administered monthly. You get paid usually at the end of the months and bills can turn up at any point, depending upon when you started a service. Any payments coming from central government, such as state pension or other benefits, are paid every 4 weeks. This means that there are 13 payments in a year. I thought it pertinent to clarify this point as other countries, such as the USA, favour a fortnightly financial cycle. Hence as a household we work around a monthly budget.
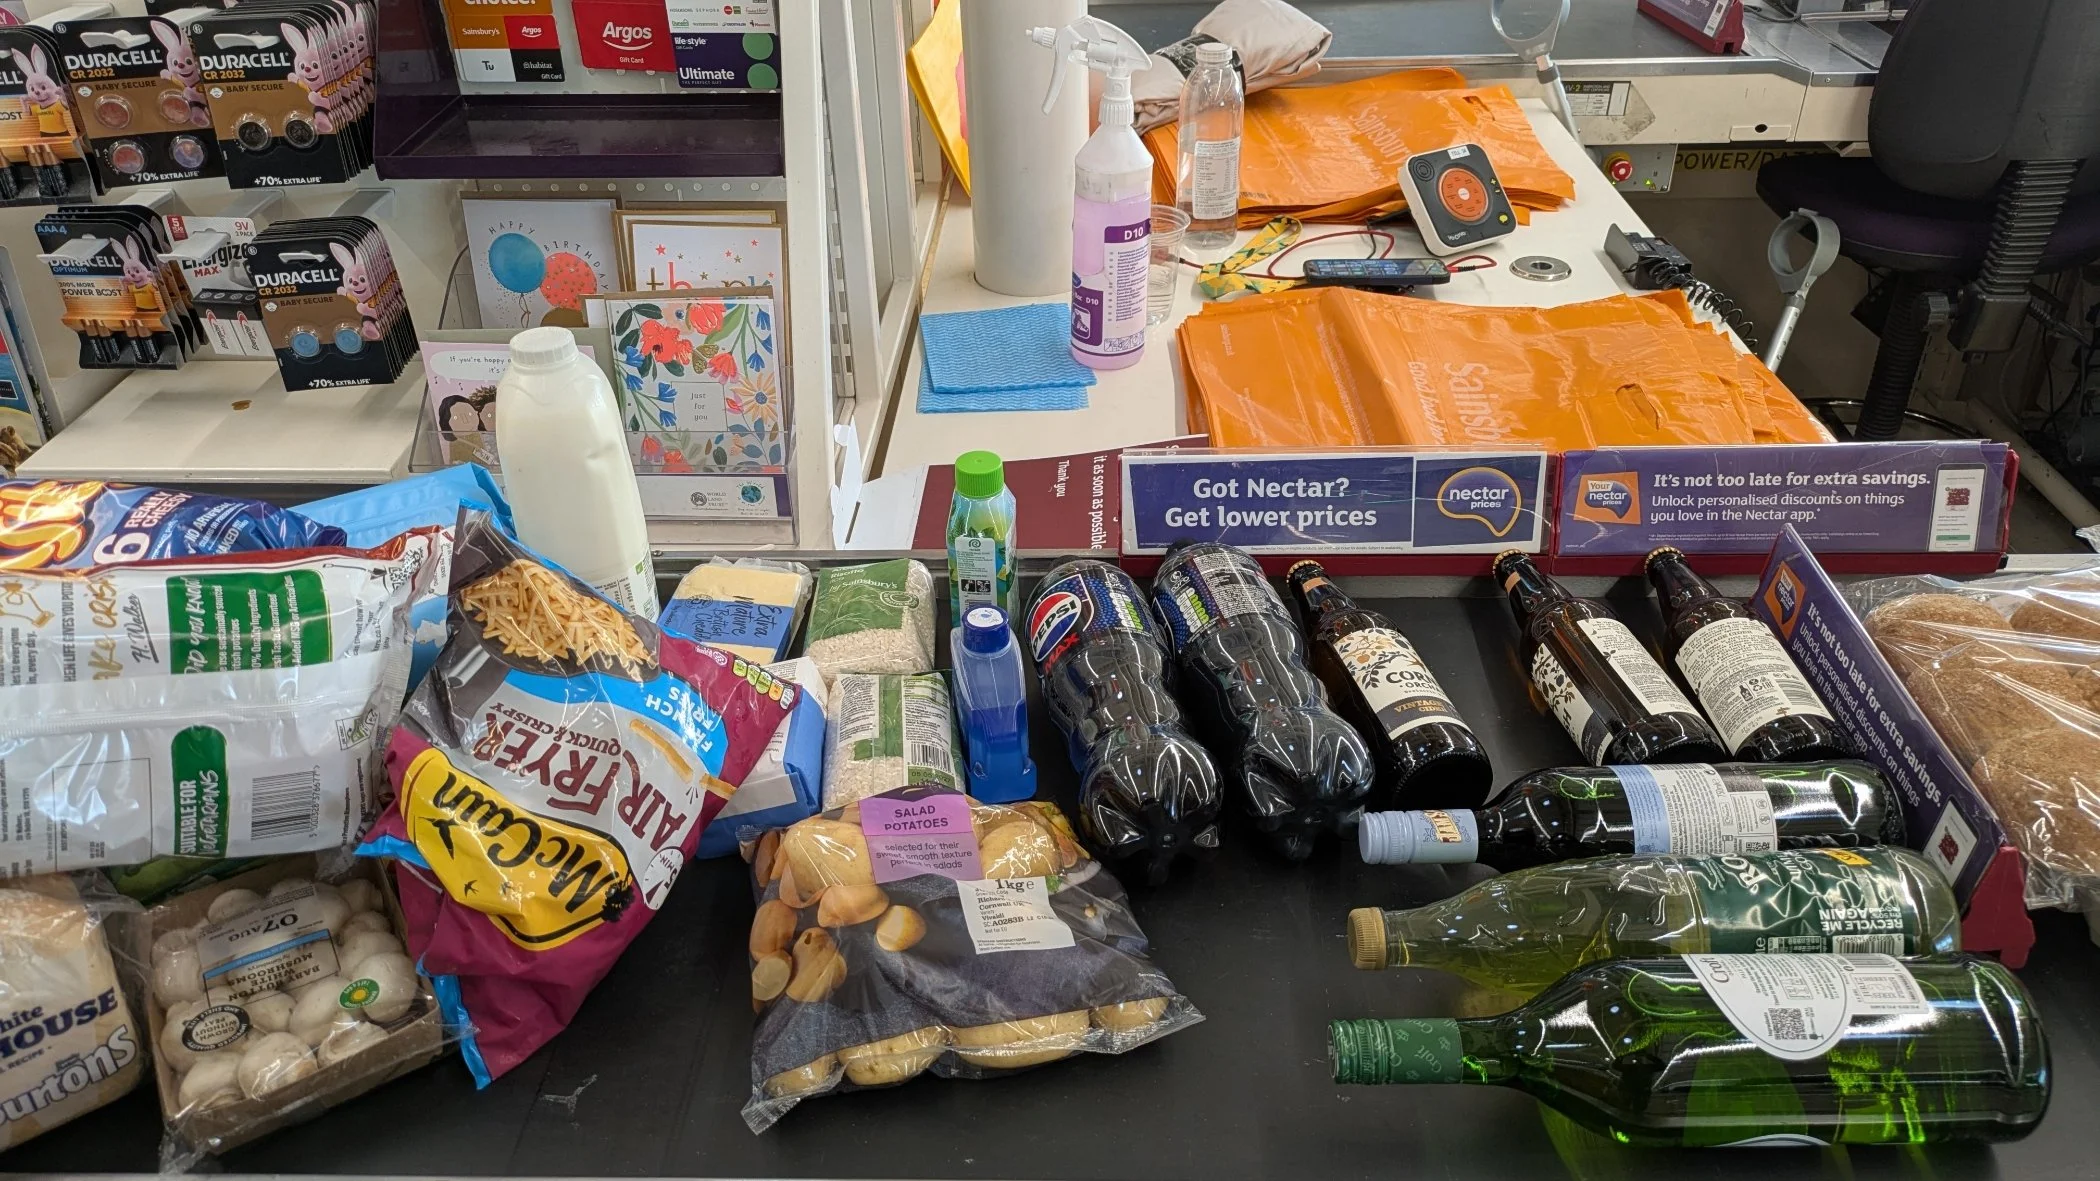
One of the things I enjoy most about having my own blog is the fact I can write about the mundane and the trivial. Mainly because so much of life falls into this category. Life defining events are all fine and dandy and certainly lend themselves to philosophical musings that make fine blog posts. However, you can get just as much mileage out of those everyday things in life with less gravitas, that we all do. Such as buying new clothes, taking out the recycling and going to buy groceries. I have written about all of these in the past. However, today I wish to broach a subject that both fascinates me but also raises my blood pressure. I believe it to be a social marker and a clear indication of an individual’s personal psychology. Yes, I’m talking about packing your groceries at the supermarket and the various rituals and social etiquette associated with it.

Sunday 6th April is the start of a new financial year, here in the UK. According to data from numerous financial and economic institutions, an estimated million plus households will be facing annual increases of £400 to £500 as the proverbial “cost of living” goes up. Everything from Council Tax to Mobile and Broadband costs are being increased. Future cost hikes are expected in our energy and water utilities. As bills start going up across the country today, average wages remain stagnant. Middle-income and poorer households have been worst hit by this wage related issue. Hence the tabloid press have labelled the start of the new financial year as “Awful April”. Hyperbole aside, this is a very real issue which due to its complex, global causes, doesn’t have a quick fix solution.
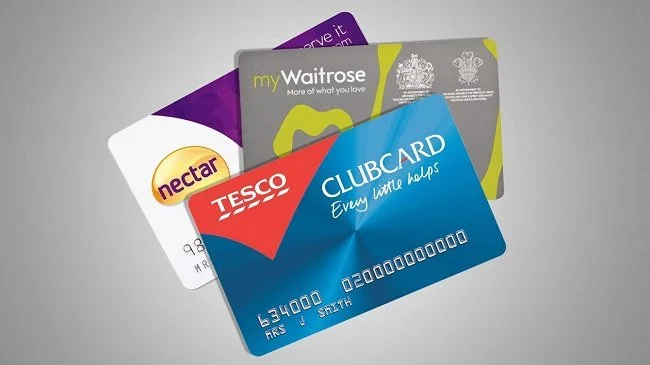
In the dim and distant past, UK supermarket loyalty cards used to be about earning points that could be traded for luxury items. This would be merchandise or services. Air Miles being a prime example. This changed over time and supermarkets moved to a system where you earned points via purchases that had a nominal financial value. The customer could then offset these accumulated points against their grocery bill. A couple of years ago, around the time the “cost of living crisis” began, some UK loyalty cards added an additional system and started offering discounted prices on specific products. For example a pack of 9 Andrex Complete Clean toilet rolls retails at the standard price of £5.95 but if you have a loyalty card, you can purchase it at the lower price of £4.65 instead.

When I was a child growing up in the seventies, my parents used local shops such as the grocers, butchers and bakers for their regular shopping needs. All were small, independent, family run businesses. Sadly, those days are long gone. Nowadays, most of us go to a supermarket or local store of some kind, for our respective shopping requirements. The frequency of such visits may depend on your pay cycle and whether you prefer to shop daily, weekly or monthly. In the UK, store loyalty has been an important factor for many years. More recently, because of the cost of living crisis, many shoppers are now going to stores where it is more economical. Store and brand loyalty are being tested and not necessarily winning. The march of online shopping has also stalled, as convenience is no longer trumping cost. Things are changing and changing fast. Who said retail was dull?
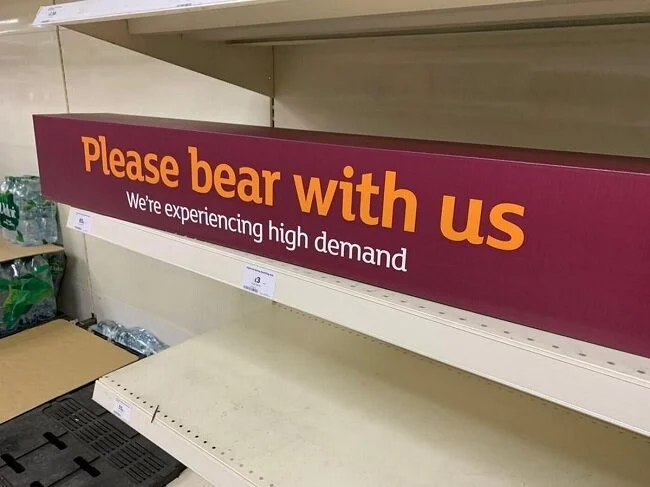
In early June I was visiting Sainsbury’s supermarket in Crayford, apparently their biggest site in the UK, when I noticed that several shelves had the following sign. “Please bear with us. We’re experiencing high demand”. At the time I thought nothing of it but then I started seeing similar notices in other stores. I then began seeing stories on some news websites about supply chain problems. This point was then reiterated on the news radio station LBC. Two month on and this issue is now finding its way into the mainstream press. McDonald’s currently cannot supply milkshakes or bottle drinks and Nando has had to close 45 branches around the UK as it has no chicken wings to serve. It is now becoming very clear that there is a big problem on the horizon, due to several complex factors. If it is not addressed this matter will only get worse with shortages directly impacting upon Christmas sales.
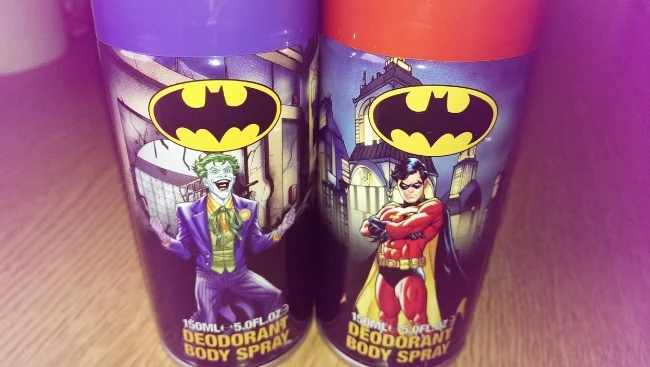
Pound shops, Dollar Stores, call them what you will, have become ubiquitous in recent years. Furthermore the public’s attitude towards them has radically changed. Where in the past snobbery may well have kept certain socio-economic groups away, it now seems that everyone is happy to use such outlets in search of a bargain. I frequent them regularly for toiletries, kitchen and bathroom cleaning products as well as tinned foods. Most products are well known named brands and the prices just cannot be ignored. Pound shops can also be a fascinating source of curious and esoteric items. I discovered such a product today.
Fighting the Cost of Living
Our household is currently trying to reduce our monthly overheads in response to the ever increasing cost of living. April is not that far away and a great many service providers will increase their rates and tariff as the new financial year begins. Then there is the ongoing effects, both direct and indirect, of inflation to consider. Although the UK inflation rate is dropping, currently sitting at 3.4% in December 2025, food inflation remains higher at 4.5%. Being based in the UK, salaries and billed services tend to be administered monthly. You get paid usually at the end of the months and bills can turn up at any point, depending upon when you started a service. Any payments coming from central government, such as state pension or other benefits, are paid every 4 weeks. This means that there are 13 payments in a year. I thought it pertinent to clarify this point as other countries, such as the USA, favour a fortnightly financial cycle. Hence as a household we work around a monthly budget.
Our household is currently trying to reduce our monthly overheads in response to the ever increasing cost of living. April is not that far away and a great many service providers will increase their rates and tariff as the new financial year begins. Then there is the ongoing effects, both direct and indirect, of inflation to consider. Although the UK inflation rate is dropping, currently sitting at 3.4% in December 2025, food inflation remains higher at 4.5%. Being based in the UK, salaries and billed services tend to be administered monthly. You get paid usually at the end of the months and bills can turn up at any point, depending upon when you started a service. Any payments coming from central government, such as state pension or other benefits, are paid every 4 weeks. This means that there are 13 payments in a year. I thought it pertinent to clarify this point as other countries, such as the USA, favour a fortnightly financial cycle. Hence as a household we work around a monthly budget.
Broadly speaking, our monthly outgoings breakdown as follows. I would assume that this is fairly universal. Council tax which funds the local authority and the services they provide. Then there are utilities such as gas, electric, water, mobile phone and internet. Most people have travel expenditure or the cost of running a car. Then there are groceries. Perhaps the biggest monthly expenditure for most people these days is paying for housing. Be it a mortgage or rent. Some of these things have very little scope to be reduced as customers have very little agency in the markets that govern them. Hence mortgages, rent and local taxation tend to increase steadily and can only be addressed by an increase in income or by moving. Travel, car and utility costs do have scope to be reduced. There are alternative vendors and a culture of changing service providers and securing the best deal. However, that only works if the vendors operate in your area.
At the end of last summer, we signed up to a fixed cost tariff from our energy provider. This is the second year that we have done this and it has proven financially prudent. It was unusually hot in the UK throughout June, July and August in 2025, hence we used a lot more power than usual trying to keep the temperature in the house equitable. The tariff meant that we weren’t hit by excessive costs for our three months of increased power usage. Other providers increased their base costs to capitalise on the heatwave. We have also given thought to having solar panels installed on the roof. We’re fortunately based in a warmer part of the UK and there are several schemes available at present that have favourable terms. However, our heating systems is still gas based and therefore wouldn’t benefit from such an undertaking. We could replace the heating system but that is sizeable capital investment. However, there are grants to help make such transitions.
Perhaps the areas with the greatest scope for financial savings are from services such as internet provisions, mobile phone tariffs and streaming platforms. We’re shortly moving to a new ISP and maintaining an identical service for half of our current cost. Both Mrs P and I have moved to SIM only phone contracts, electing to get off the expensive, yet pointless upgrade treadmill. We have also cancelled or replaced some streaming services. I am also trying to eliminate the costs associated with certain software services like Office 365. All of these sorts of saving can initially appear quite small and possibly inconsequential. However, once you add them to a spreadsheet and see the accumulative savings, they prove their worth. Exactly the same can be said with regard to supermarket loyalty cards and their respective members discounts. We no longer shop exclusively at just one supermarket but will go to specific stores to get deals on frequently used products.
There is one other area of potential financial savings that can be addressed but is often neglected due to customer apathy and fear that it may all go wrong. That is changing bank accounts, credit cards or moving your savings. It never ceases to amaze me how some folk will chase a deal online or in the actual stores but are quite content to let their wages stagnate in a current account with little or no benefits, or who miss out on higher interest rates by not moving their savings around. Legacy banks are no longer the best default options and there are now plenty of new online only institutions that are trying to increase their market share. The incentives on offer are not just purely money based. Many banks offer “freebies” such as subscriptions to services such as Netflix and Spotify. Plus transferring an outstanding credit card balance to a new providers can still yield substantial benefit. I guess people treat their banking differently from other services, when it really isn’t.
However, I don’t advocate turning cost savings into an all consuming ideology. For example, I will from time to time buy “reduced” label items in the supermarket but I have no intention of living exclusively that way. Some brands have a cost that simply doesn’t fluctuate and don’t have an immediate lower cost equivalent. For example, I won’t eat cheap biscuits from pound stores just to save a few pennies. I’d rather have some good quality indulgences from certain stores, than a larger quantity of inferior products, from a discount outlets. Like many things in life, looking for a deal needs to be tempered with common sense. Another essential tip is to visit websites that collate information on the best deals available, such as Uswitch in the UK. Or to follow people like Martin Lewis on social media, who have made consumer advice their career. Making savings to your monthly expenditure is no longer an optional extra but an imperative. Good luck in your pursuit of a good deal.
When I was a child, I quickly learned never to say within earshot of my parents that I was bored. It was quickly met with a response along the lines of “an intelligent mind is never bored” or more worryingly “if you’ve got nothing to do, I’ll find you something” which meant a chore or Herculean task. Being a child of the seventies and due to my parents fundamentalist approach to declarations of boredom, I quickly discovered numerous ways to occupy myself. The default solution was a book or comic. I always liked reading as a child and had plenty of books to choose from. I also had numerous of comics as an alternative to a hefty tome. I would also draw and paint. My father use to work during the summer holidays as a design draftsman and as a result, we always had plenty of paper in our house. Then of course there were toys and such like. Hence I learned the art of keeping myself busy.
When I first started this series of posts back in 2023, they were originally intended to provide a useful overview into UK (mainly British) slang. US slang is ubiquitous globally due to the pervasive nature of American culture. Hence most people have a good grasp of its nuances. However, the proverbial door does not swing both ways. Hence most people will watch British TV dramas or read popular novels and can be quite bamboozled by some of the phrases that are used. That is what I was trying to address. However, over time this entire enterprise now reads like a some sort of Guy Ritchie film with Colin as the anti-hero. That notwithstanding, hopefully the list of slang phrases below will prove useful to know, if you ever visit the UK or tour around London. As ever I have given an example of their respective use. Feel free to ask questions if anything needs clarifying, or you wish to leave a comment with examples of you’re own national and regional slang.
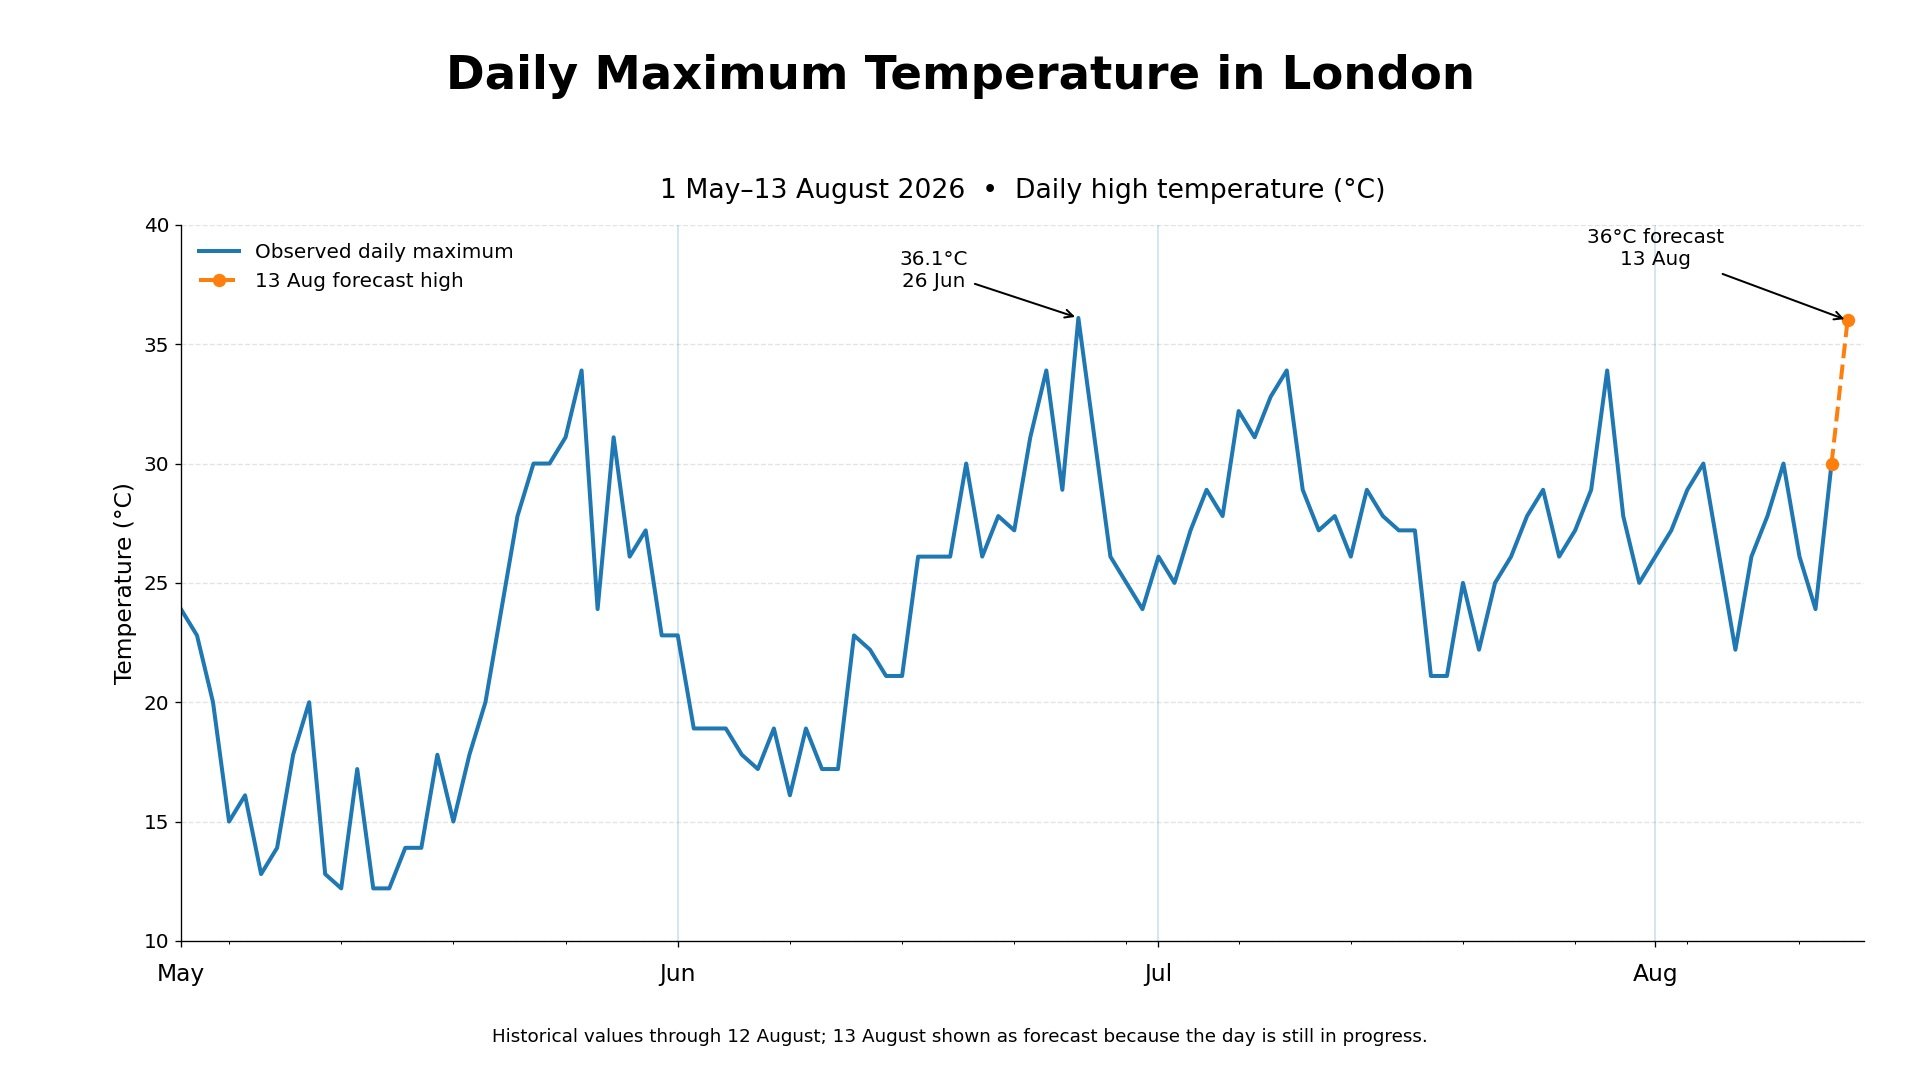
As I write this post, the temperature in Greater London is 33°C (91.4°F). This has become a regular occurrence since the middle of May onwards. High temperatures are fine when you’re on holiday mainly because you’re off work and at your leisure. You don’t have to perform the usual daily task that life requires of you such as work, shop, cook, clean etc. Furthermore, if you’re on vacation you’ll probably be staying at a resort or hotel that is fully air conditioned and you’re dressed accordingly. However, if you’re still performing you’re daily routine such as commuting to work and spending time in an office that wasn’t built with such external temperatures in mind, then 33°C is frankly a pain in the ass. Oh and if you’re one of those people who always respond to discussions such as this with “well I live in Riyadh and it’s 40°C here”, please sod off. You live in a desert which is dumb to begin with. Plus this is not a commensurate comparison. Temperatures are rising in the UK. It’s always hot in Saudi Arabia.
If you visit the websites for such UK tabloid newspapers as the Daily Express or the Daily Mail you will no doubt encounter prominent stories about Megan Markle, Nigel Farage and “immigrants”. If these two august institutions are short of column inches, they’ll run a piece about how some former celebrity has had the unmitigated gall and temerity to get old. I mean WTF? How dare they do what human beings are genetically disposed to do. It’s outrageous. Similarly, head over to the Unherd website and you’ll find foam flecked tirades regarding spurious points of contention over dubious subjects. Often the topic being harangued is incredibly niche and I’ve never heard of it before or even considered it being a thing. These sort of talking points are not about informing, debating and most certainly aren’t about thinking. They exist to provoke reactions.
Before we start, let me explain to those readers outside of the UK, the significance of a Dairy Milk Freddo chocolate bar and its relevance to this post. The “Freddo” is an 18g (0.63 oz) chocolate bar, in the shape of an anthropomorphic frog. When it was re-launched by Cadbury in 1990 (it had previously been manufactured by an Australian confectionery company in the seventies), it was priced at 10p (£0.10). It remained at that price until 2005 when a 1p to 2p increase began to occur each year. By 2016 Freddos were retailing at 25p. However, the following year the price “lept” to 30p with an increase that was double its usual yearly rise. This led to public outrage across social media. Since then the price of a Freddo has waxed and waned. Tesco supermarket reduced the price back to 10p as part of their centenary celebrations. The post COVID price in 2022 hit 49p. At present, the average price of a Freddo in the UK is somewhere around 35p.
Over the last 10 years, I’ve written several blog posts about my personal working experiences and my career, such as it was. I touched upon working specifically in IT and how that industry changed over time, both technically and in the way that other people perceived it. I have also given my thoughts on the social dynamics of the modern work environment and the way we interact with our colleagues and employers. That is another area that has changed dramatically. Naturally my retirement from full time work has been written about, as it is such a radical change in one’s life. Especially if you’re the sort of person who is clearly defined by their job, which I personally was not. This time, I want to share a few thoughts I have about what I miss about “going to work” and “having a job”. I’m not sure if “miss” is the right word. Perhaps it is more a question of things being absent. Either way, there are some aspects of being employed that I use to enjoy or at least found beneficial that I now no longer experience.
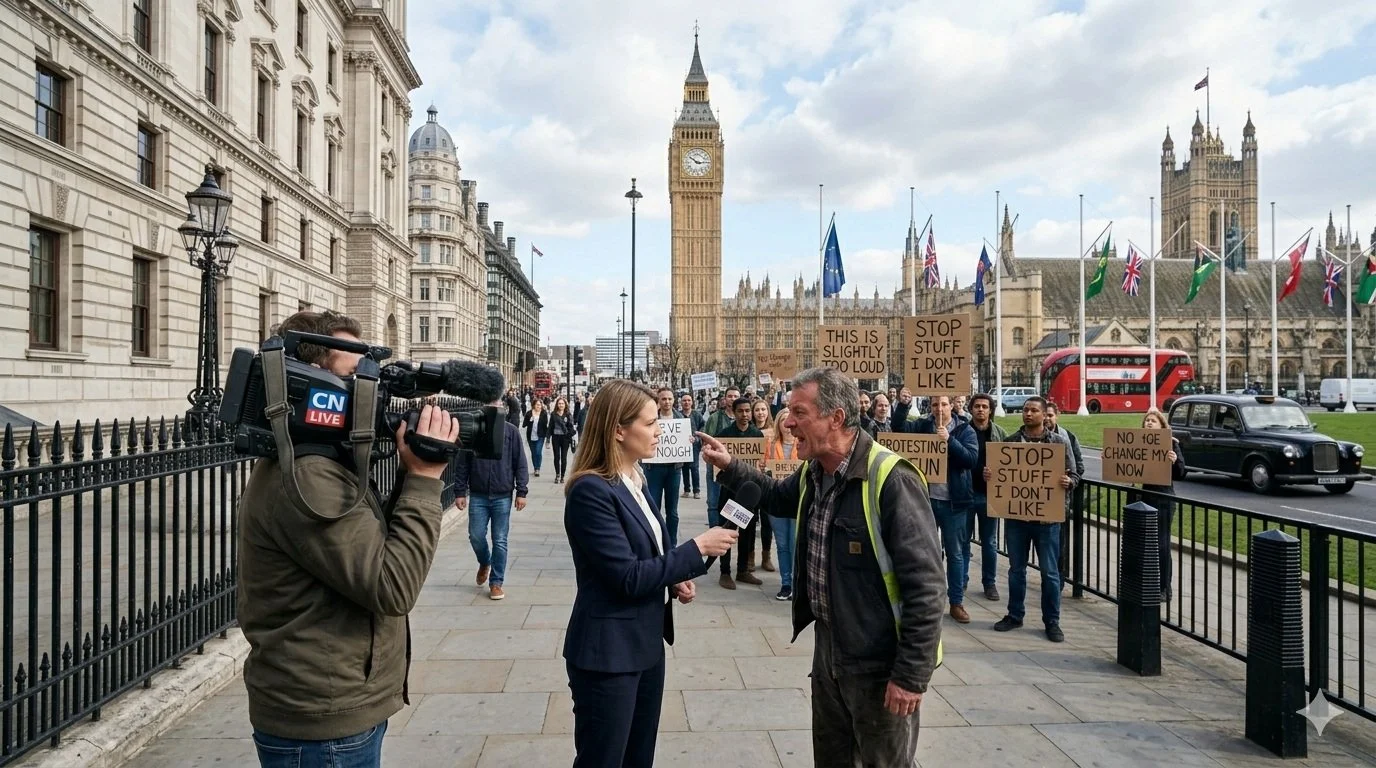
UK Prime Minister, Sir Keir Starmer has resigned and intends to leave office before the parliamentary summer recess. By then Andy Burnham will more than likely be voted leader of the Labour Party and by default will become the new Prime Minister. Due to the current size of the incumbent Government’s majority, there is no pressing reason for a General Election that the UK’s right wing tabloid press is currently calling for. Whether this provides the Government with the reset they’re hoping for when Parliament reconvenes in autumn remains to be seen. With seven Prime Ministers coming and going in a decade, there are some serious questions to be asked about the current state of UK politics. However, the mechanics of contemporary politics, the decline of clearly defined ideologies and the people that seek elected office to be our leaders are only half of the problem. The other major impediment to the UK’s democracy functioning properly is the electorate.
The UK Government has formerly announced its intention to ban under-16s from using social media. This is due to increasing public pressure that “something must be done” about the perceived iniquities of many online platforms. However, as with most complex social problems of this nature, no one has any clear or practical ideas as to what that “something” is. It remains a nebulous, non-specific panacea and clearly someone else’s job to identify and implement. As ever, why choose a nuanced and multifaceted solution to a complex problem, when it is far easier and politically expedient to just “ban” something. The former requires effort and a degree of thinking. If such an approach fails it also means that those who came up with it now carry the can. The latter dumps the problem in the lap of various third parties, who can then be conveniently blamed when the ill conceived policy fails.
Every Thursday, Mrs P volunteers at a food bank that is run from a local church; Avery Hill Christian Fellowship. Today there was a shortage of staff so I agreed to help out. It proved to be an equitable arrangement as she collated the various orders and I packed the bags and took them to the respective clients. The food bank itself is organised and administered by the Trussell Trust, a UK based NGO and charity providing emergency food and support to people locked in poverty. It is open for 2 to 3 hours a week depending upon demand. During today’s session we served just six people. Some weeks its can be triple that amount. Upon closure, a member of staff from the Trussel Trust did a stock take and collated a list of what was needed. This is provided by various local church communities via parishioners donations, as well as local supermarkets who have an arrangement with the trust to provide surplus stock or good approaching the end of their sales window.
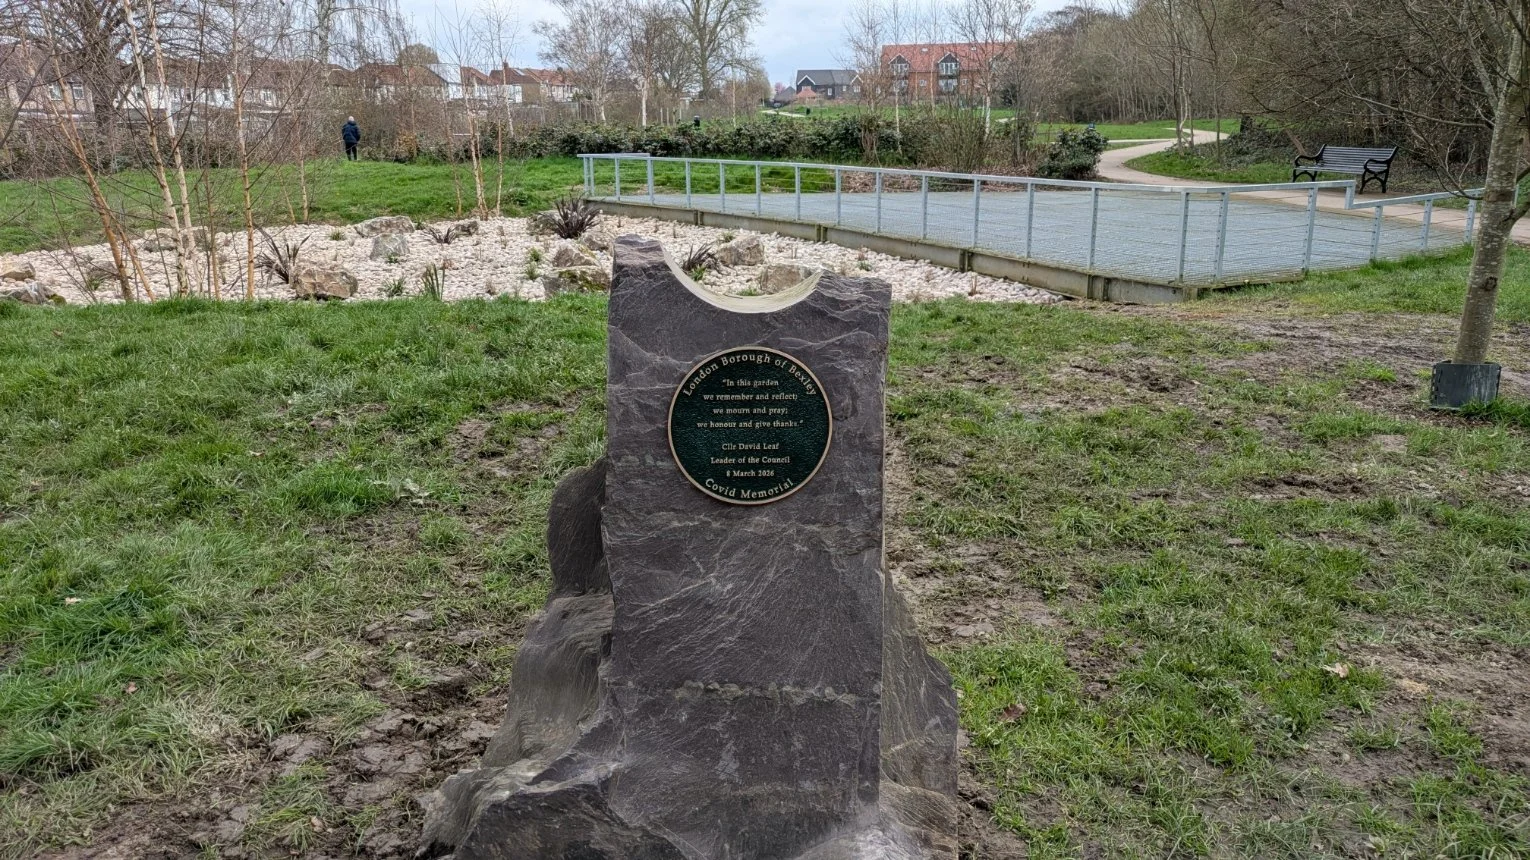
There are approximately 4000 parks and green spaces in Greater London. Bexley Borough alone has over 100. Public parks and green spaces are vital to modern cities, providing essential health, environmental and social benefits. They boost physical and mental wellbeing by reducing stress and providing a place for exercise. Furthermore they enhance urban sustainability, mitigate heat, and provide a sustainable environment for a wildlife. Parks are often a venue for social activities and events and as such are an important part of the local community. Going to the park has always been a part of my life. I live next to Old Farm Park in Sidcup and have made use of this recreational space throughout my life. I used visit with my parents in the seventies, when I was a child. Thirty years later my son, father in-law and I would fly kites there. Now I take my grandchildren to Old Farm Park as it now has a playground.
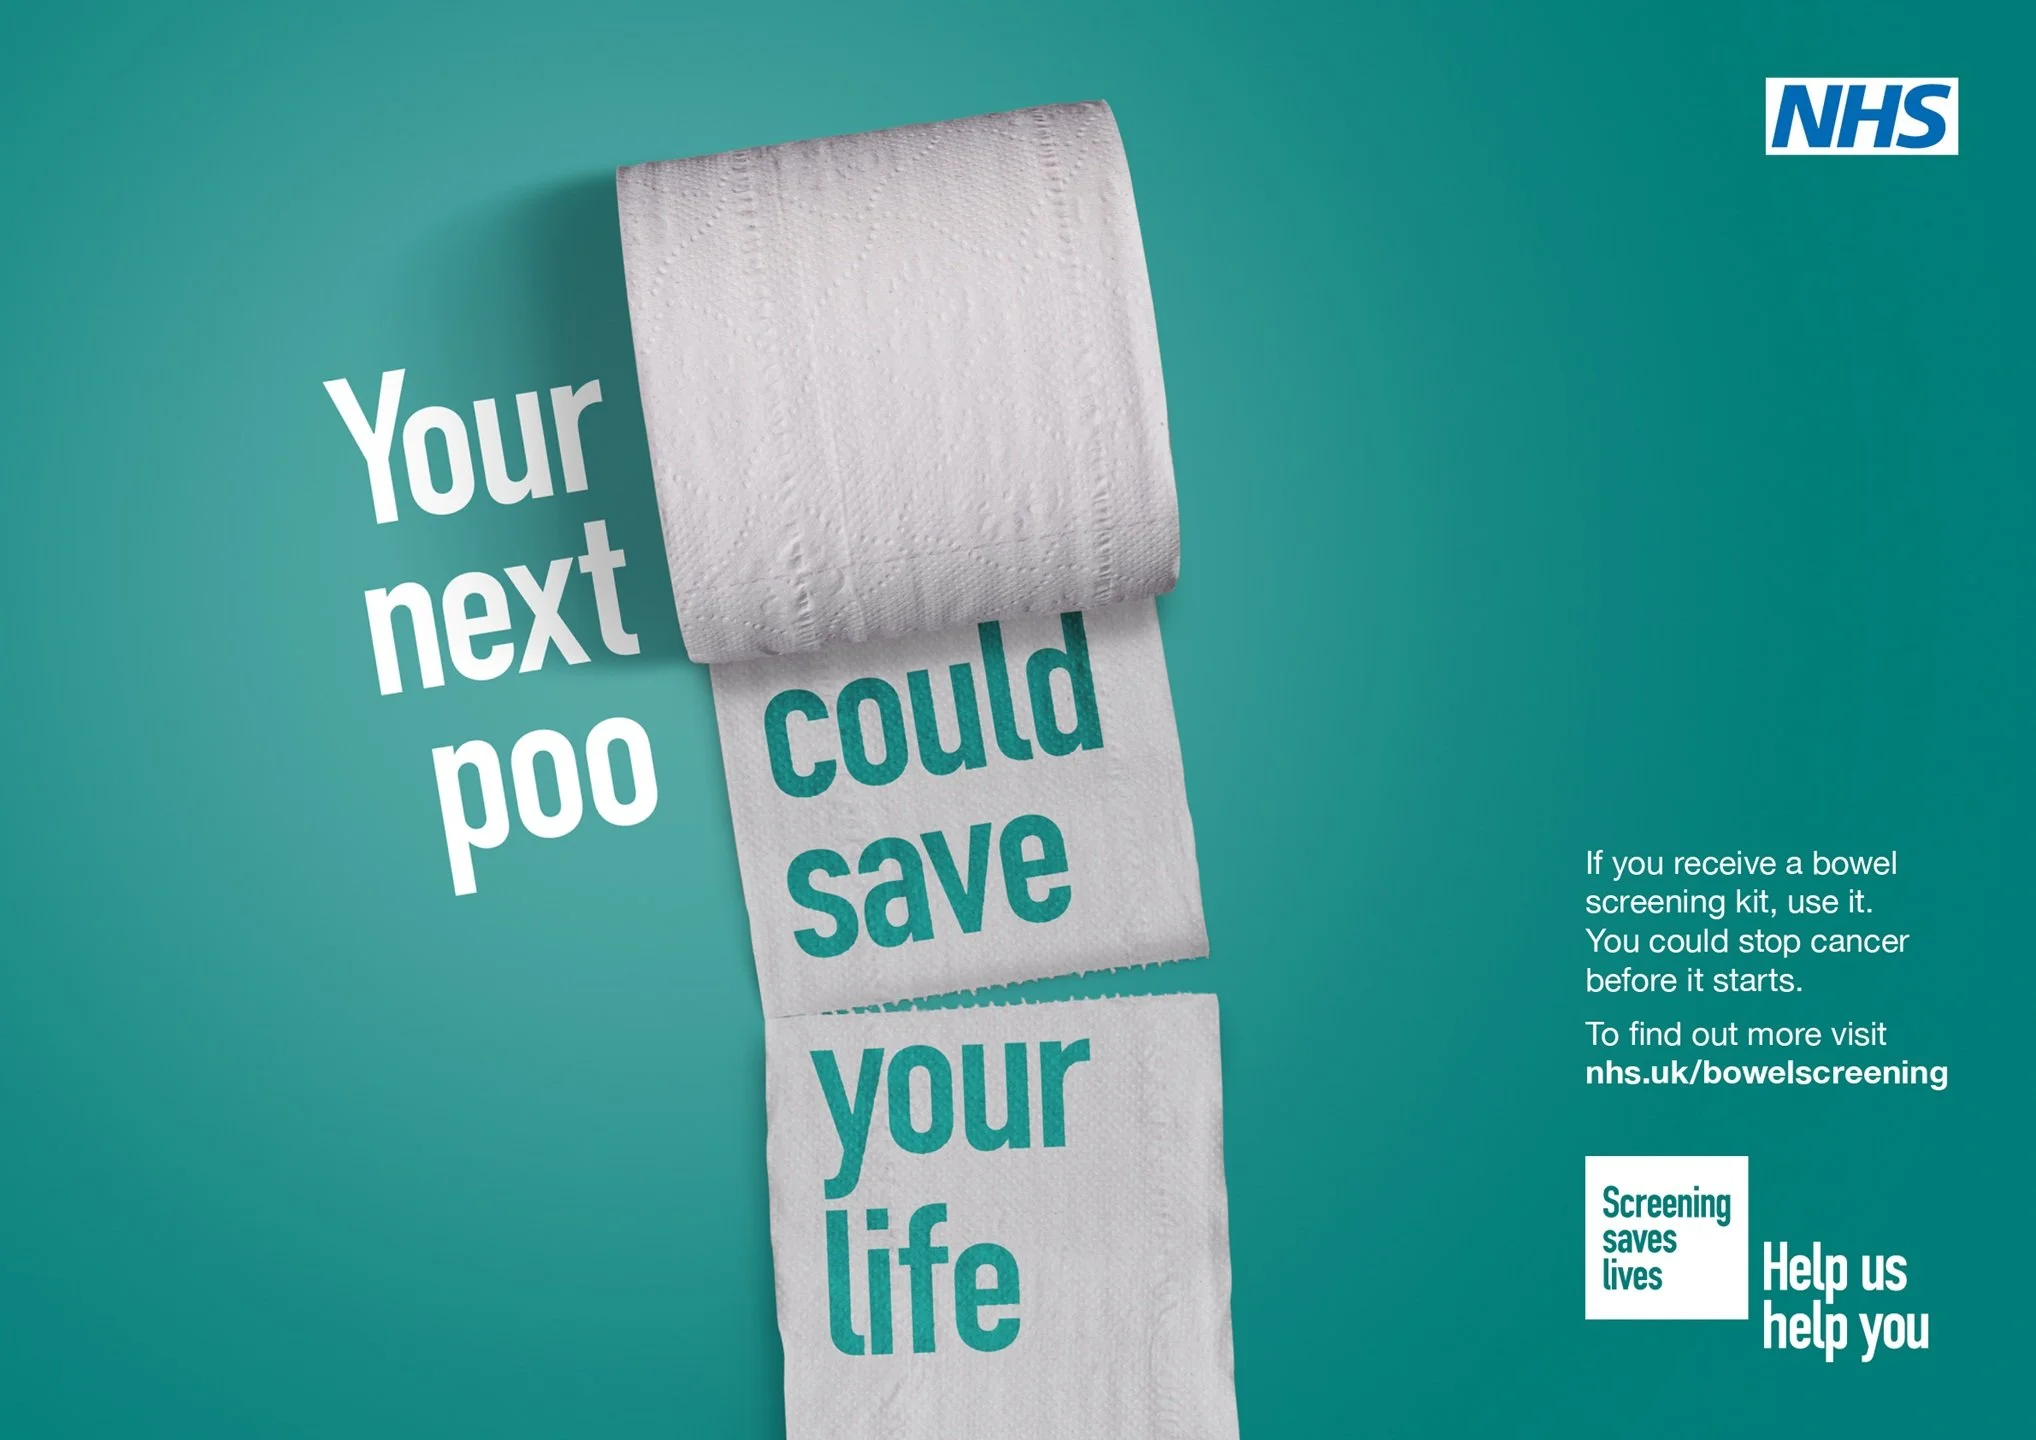
Being a 58 year old man, I welcome any undertaking which can potentially improve my health. One such thing is proactive screening and testing. The UK National Health Service has started doing a lot more of this in recent years, mainly because diagnosing a problem and treating it early is far more efficient and cost effective than retroactive action. Hence this policy and my age is why I was recently sent a NHS Bowel Cancer Test Kit via the post. This screening service takes place every two years for people aged 50 to 74 in the UK. The kit is very quick and simple to use. A sample of your stool is sent via a prepaid return envelope for testing and the entire process is free of charge. Upon receipt, the laboratory test determines whether there is any blood present in your stool, which is a potential indicator of bowel cancer. If detected, an early diagnosis greatly improves any subsequent treatment outcomes.
I like learning things. I always have. During my middle school years I thought I was a mediocre student and often I wouldn’t apply myself. According to an old school report this was because I was “too busy indulging in Tomfoolery”. Then I had the positive experience of meeting an exceptional teacher. Their lessons were the highlight of the week as they had an ability to make the subject matter, Classical History, utterly compelling and relevant. The teacher in question also treated us like adults and the class benefitted from only having five pupils. This really brought home to me that a lot of disinterest and underachievement in education is linked to the paucity of some teachers. One bad teacher can undermine the good work that all the others can do. Perhaps it has improved nowadays?
I’ve had an interest in the paranormal since I was a child. My mother always got books out of the library about ghosts and UFO phenomenon, so in some respects I was influenced by her reading habits. As a child such tales were by default interesting and any potentially scary element naturally made them more enjoyable. However, my father being an academic had taught me to question everything, so I felt fairly evenly equipped when exploring these subjects. Further to this point, over the years I have learned that humans have a very unique perspective on the world. We are hard wired to see patterns, regardless of whether they’re there or not. Our senses can also be fooled and often are. Perhaps the most important aspect of our nature that impacts upon any analysis we make into the paranormal is our penchant for creating stories. Hence unusual experiences can be subconsciously misremembered and “retconned” to form more precise narratives.
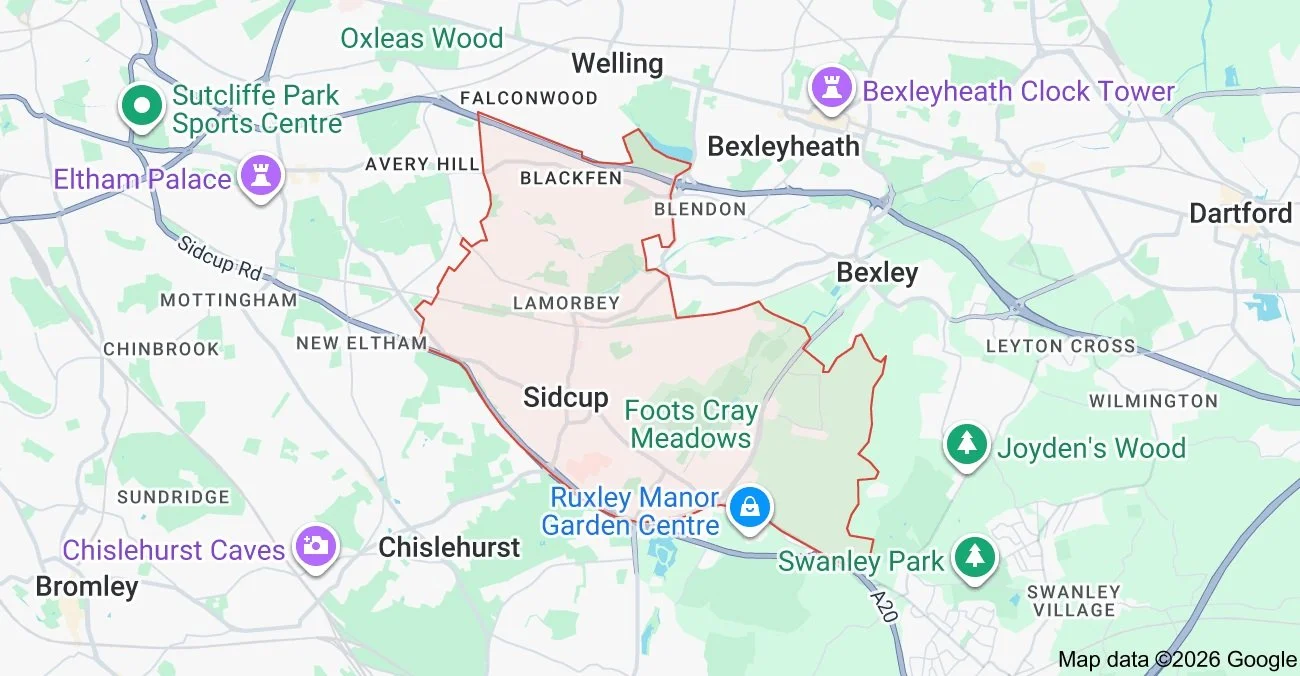
I have lived in Sidcup, in South East London, for most of my life. The first two schools that I went to were local and within 15 minutes walking distance. My Doctor’s Surgery and Dentist are only a few streets away, as is the barbershop that I’ve frequented since 1970. I now have my haircut by the son of the original barber. My point being that Sidcup has everything that residents immediately need. There’s a local hospital, good public transport networks and a broad range of shopping and restaurant facilities. It also has several parks with lakes, sport facilities and children’s play areas. It is a microcosm of the concept of suburbia with its residents commuting into Central London or out into Kent for work. People move here to raise families and end up staying. My parents lived here for 62 years.
Our household is currently trying to reduce our monthly overheads in response to the ever increasing cost of living. April is not that far away and a great many service providers will increase their rates and tariff as the new financial year begins. Then there is the ongoing effects, both direct and indirect, of inflation to consider. Although the UK inflation rate is dropping, currently sitting at 3.4% in December 2025, food inflation remains higher at 4.5%. Being based in the UK, salaries and billed services tend to be administered monthly. You get paid usually at the end of the months and bills can turn up at any point, depending upon when you started a service. Any payments coming from central government, such as state pension or other benefits, are paid every 4 weeks. This means that there are 13 payments in a year. I thought it pertinent to clarify this point as other countries, such as the USA, favour a fortnightly financial cycle. Hence as a household we work around a monthly budget.
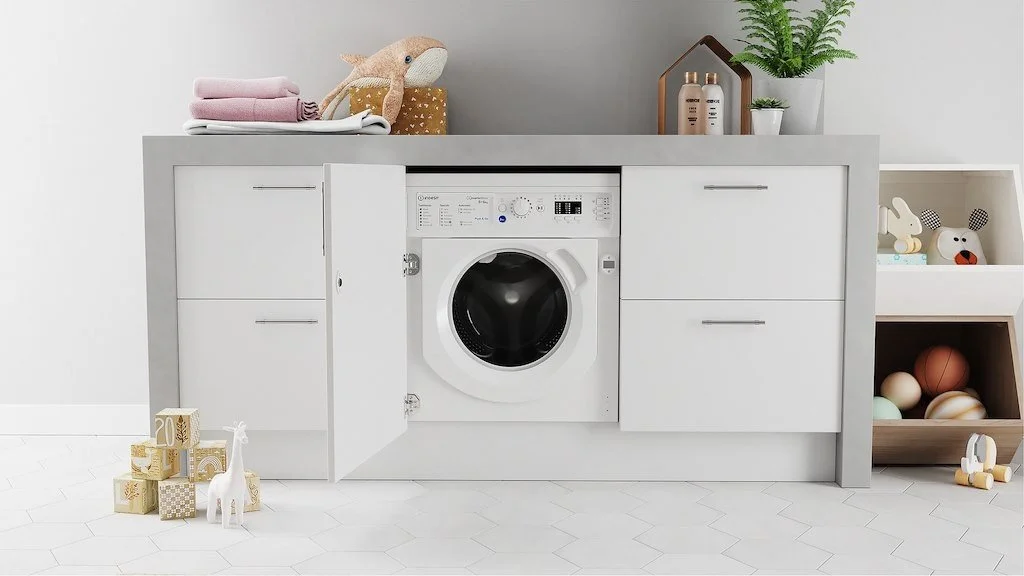
I try not to let the failings of contemporary capitalism get to me but such a mindset is very hard to maintain. From time to time it does just piss you off and you know damn well that there’s nothing you can do about it. So to begin this tale, at the end of November, our Indesit washer/dryer gave up the ghost after a valiant twelve year lifespan. As a result of this household appliance’s stirling work, it was decided to buy another from the same manufacturer. Their website informed me that the model that had just broken was no longer being produced. However, it recommended two newer appliances that had comparable specifications and more importantly the same size. This washer/dryer had to fit into a fitted kitchen unit. To cut a long story short, a model was chosen, purchased, delivered within 48 hours and installed. The broken predecessor was subsequently taken away. The wonders of modern consumer culture!
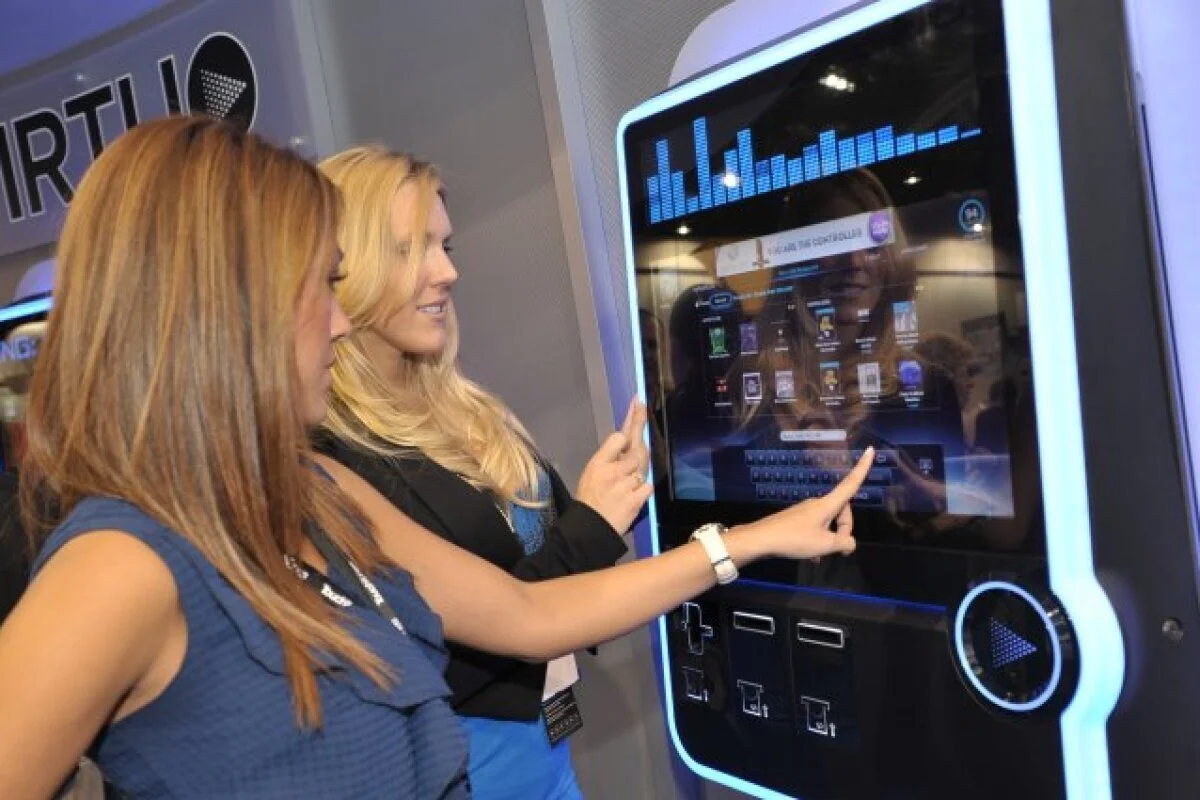
I was in a pub last night, catching up with friends before Christmas, when I noticed on the wall something I haven’t seen in a pub for a very long time. A jukebox. In my experiences most of the pubs I go to take one of the following two approaches to background music. They either have a sound system and exclusively manage any music via personally curated playlists from behind the bar. Or they have no music at all. The Wetherspoons chain of pubs broadly follow the latter policy and actively use it as a marketing point. Quiet pubs for clientele that just want to talk can be popular. Hence finding an accessible jukebox was a blast from the past. During the late eighties and early nineties, I regularly visited my local pub and often used the jukebox there, which at the time, was operated by an ever changing store of CDs. The jukebox I encountered last night was digital.
Today is my 58th birthday. It would appear that I have existed for nearly six decades. Put another way, I am over half a century old. All of which has given me pause for thought with regard to the passage of time. A phrase that is often bandied about, but what exactly does it mean? As I understand it, the “passage of time” refers to our perception of the flow of time and how we experience its movement. This is something distinct and different from objective time as measured by clocks. Our subjective experience of time can vary due to multiple factors. Two common examples are how time can feel like it's flying by when we're having fun and enjoying something or dragging its feet when you’re enduring something dull. Other factors are whether we are applying ourselves to a task, concentrating and general activity. Such focus can make time pass quickly.
When Mrs P and I moved into our current home, over twenty years ago, we were both working full time. As the garden was poorly maintained and neither of us had any horticultural skills, we decided to employ a gardener. At the time it was a practical solution to the issue of garden maintenance and remains so today. Hence it is a service we continue to use, although our personal health is now the main reason we pay a gardener.
In July the UK Government introduced the Online Safety Act which requires age checks for accessing sexually explicit content online. As a result of this, Pornhub, the 19th most visited site on the internet, has reported a 77% decline in UK traffic. Furthermore, according to the UK regulatory body, OFCOM (The Office of Communications), overall visits to pornographic websites from the UK have fallen by 33%. Naturally, those who championed this legislation are claiming a moral and political victory. However, once you consider what these facts actually mean, they paint a somewhat different and potentially more worrying picture. It would be staggeringly naïve to think that UK visitors to Pornhub have ceased visiting such sites due to the age verification requirements. The more likely explanation is that UK porn consumers are now using VPNs to circumnavigate these restrictions and that this traffic to Pornhub is now recorded as coming from elsewhere.
Formal education in the UK is a structured process, starting at early years learning and continuing through to higher education at university. Some aspects of the educational system are mandatory, whereas others are optional. At present, children in the UK must start full-time education from the age of 5 and remain until the age of 16. After this age, they are no longer required to attend school per se but must remain in some other form of education or training, such as a vocational college or an apprenticeship. Many students remain at school until 18, as there are specific exams to be obtained that are required for a subsequent university placement. Here is a breakdown of the current process as it exists in the UK.
I don’t know if you have noticed that there are quite a lot of companies that have names taken from Tolkien’s Legendarium. At first glance, this seems innocuous enough. Tolkien’s writings grew in popularity over the seventies and eighties but since the release of the film trilogy at the start of the twenty-first century, his work has become more well known and been assimilated into our wider pop culture. Hence, it seems quite logical that a startup tech company, for example, would choose a name from his writings. No doubt the founders grew up reading The Lord of the Rings and are fans. That all seems plausible. However if you take a further look, it gets somewhat more complex. Here are four companies that have Tolkien based names.
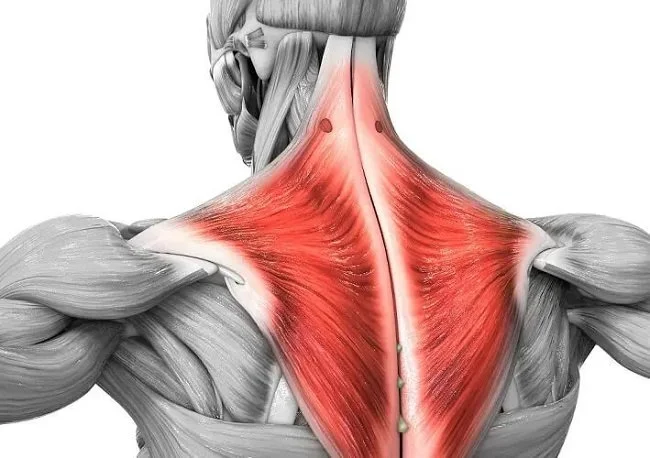
Last Wednesday, I woke up with what I thought to be a crick in my neck on the left hand side. I assumed this was simply due to sleeping awkwardly and so I self medicated with some non-prescription pain relief and judicious use of a heat pad. Unfortunately, the problem has persisted and in the last 24 hours it has become much worse. I awoke this morning at about 5:00 AM and as I sat up in bed, an intense pain ran up the left side of my neck and behind my ear. It took several attempts for me to get out of bed because if I turned my head in either direction or inclined my chin, the pain would again run up the side of my neck. Sitting down, getting up and raising my arms caused similar results. While dressing, I attempted to pull a t-shirt over my head. The pain in my neck on this occasion was so severe that I yelled out loud and nearly blacked out.
I am a non-driver. If you wish to know the specifics of how this situation came about, feel free to read the post I wrote about it back in early 2018. To be succinct, I don’t drive, I’ve never learned how and have never owned a car. I don’t feel that I’ve missed out. In fact I feel quite the opposite. I think I’ve dodged a major hassle and expense in life. Mrs P, my significant other, is the designated driver of our household. She owns a car, insures it and maintains it. She also mainly pays for the petrol, whereas I pick up the tab for other things such as lunch or hotels when we travel. All I have to do is make like Iggy Pop if we go anywhere. The most I am ever called upon to do is navigate using Google maps and Android Auto. Fortunately, Mrs P enjoys driving. Always has done. Hence I look upon this situation as an extremely fortunate and equitable arrangement.
I am getting old. I shall be 58 in December. Now, as soon as you say something like that these days, some folk will get uncomfortable and say things like “age is relative” or “you’re as old as you feel”. Well I don’t measure my age in geological terms, so it’s not relative and I’m not feeling anyone especially young at the moment, so both schools or thoughts can sod off. I am getting old by the yardstick we measure human life by, namely years. I have specific, age related health issues and I just don’t feel as energised as I did a decade ago. There are minor signs, such as deciding to go to bed earlier and taking longer to get dressed after taking a shower. I’m not at death’s door but I am slowing up physically. It would also appear that my reactions are also slowing down as I tend to get massacred in any FPS I play these days. So far, my mental faculties seem to be holding up. However, that is the one thing I worry about the most. The potential loss of cognitive abilities scares the shit out of me.
Foots Cray Reuse and Recycling Centre is the fancy name of our local dump. A few decades ago, this was no more than a scrap yard. The rubbish and bric-a-brac left by the public was sorted and scavenged for resaleable scrap. Everything that was left was subsequently sent to landfill or incineration. Much has changed. Today it is the embodiment of the modern recycling ethos. The recycling centre is a well managed, carefully segregated site providing safe disposal of a wide variety of household and garden waste. Wood, metal and hardcore are recycled and there is similar provision for a multitude of electrical goods. Plastics, oils, paint, batteries can be safely disposed of. I have yet to find a home item that they do not have provision to dispose of. The Foots Cray Reuse and Recycling Centre has won awards for the service it provides and is considered one of the best facilities of its kind in the South East of the country.
One of the things I enjoy most about having my own blog is the fact I can write about the mundane and the trivial. Mainly because so much of life falls into this category. Life defining events are all fine and dandy and certainly lend themselves to philosophical musings that make fine blog posts. However, you can get just as much mileage out of those everyday things in life with less gravitas, that we all do. Such as buying new clothes, taking out the recycling and going to buy groceries. I have written about all of these in the past. However, today I wish to broach a subject that both fascinates me but also raises my blood pressure. I believe it to be a social marker and a clear indication of an individual’s personal psychology. Yes, I’m talking about packing your groceries at the supermarket and the various rituals and social etiquette associated with it.
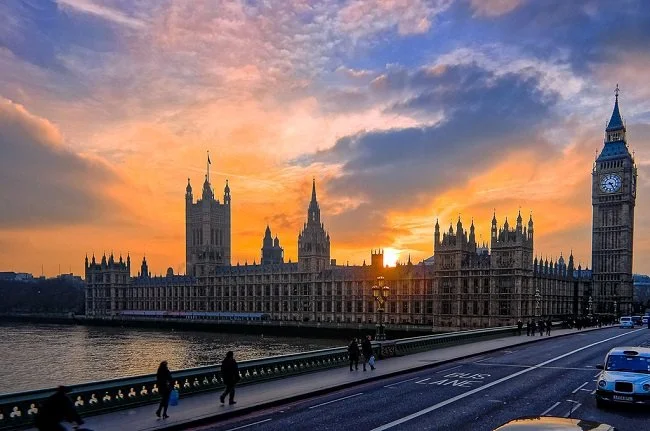
“Managed decline” is a phrase that refers to the processes associated with the end of a specific lifecycle, with the goal of minimizing costs or other forms of loss. The concept originated in business where it referred to the management of companies and industries. More recently it is used in wider contexts. The concept gained prominence with regard to urban policy, particularly in the UK during the eighties when several major cities suffered economic and political collapse. Of late, the term has been applied to the UK, encompassing a systematic weakening of the economy, social structures, and cultural values, as well as its global political and diplomatic force. In each case, managed decline involves making strategic choices about resource allocation and accepting the consequences of those decisions. It is a complex issue with ethical and practical considerations, often sparking debate about the best way to address decline and reverse the process.
It’s been five years since the COVID-19 global pandemic. At the time it was an utterly alien and tumultuous experience. However, due to the way numerous institutions responded (but not the government), many people thought there would be a great deal of social and political change in the UK afterwards. The pandemic highlighted the impotence of the NHS, as well as those who work in jobs designated as essential. It also shone a spotlight on many of the country’s inequalities. Due to our national character, a real sense of community emerged. Something that had been absent for a very long time. Briefly, we got a glimpse of what the UK could be when we all broadly worked together. There was a sense that now was the time to change the status quo. Sadly, nothing changed. As soon as the vaccination program was launched, the UK quickly slipped back into the mire it’s been wallowing in since the end of WWII.
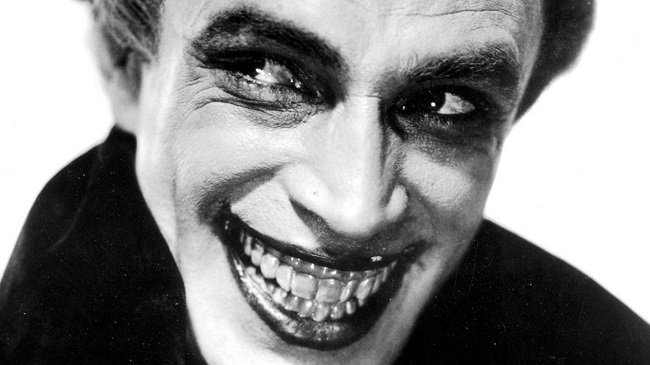
Prior to writing this post, I clocked a picture on a news website of the now disgraced TV presenter (and nonce) Gregg Wallace. I noticed that he doesn’t smile as such but tends to “gurn” instead. So does UK politician (and cunt) Nigel Farage. He always has his mouth open and his face contorted in some curious rictus, in most of the pictures you see of him. Mind you, I also don’t photograph especially well and any pictures of me smiling tend to look sinister or with a heavy hint of irony. The bottom line is not everyone is good at smiling. It doesn’t come naturally to all of us. This can be a problem at times or in social situations, because smiling is an integral part of our culture. On many occasions, I’ve been walking along, my face in a state of natural repose, only to be harangued by some twat shouting “cheer up, it may never happen”. A phrase I haven’t quite fathomed out, even to this day.
"Awful April" and the UK Cost of Living
Sunday 6th April is the start of a new financial year, here in the UK. According to data from numerous financial and economic institutions, an estimated million plus households will be facing annual increases of £400 to £500 as the proverbial “cost of living” goes up. Everything from Council Tax to Mobile and Broadband costs are being increased. Future cost hikes are expected in our energy and water utilities. As bills start going up across the country today, average wages remain stagnant. Middle-income and poorer households have been worst hit by this wage related issue. Hence the tabloid press have labelled the start of the new financial year as “Awful April”. Hyperbole aside, this is a very real issue which due to its complex, global causes, doesn’t have a quick fix solution.
Sunday 6th April is the start of a new financial year, here in the UK. According to data from numerous financial and economic institutions, an estimated million plus households will be facing annual increases of £400 to £500 as the proverbial “cost of living” goes up. Everything from Council Tax to Mobile and Broadband costs are being increased. Future cost hikes are expected in our energy and water utilities. As bills start going up across the country today, average wages remain stagnant. Middle-income and poorer households have been worst hit by this wage related issue. Hence the tabloid press have labelled the start of the new financial year as “Awful April”. Hyperbole aside, this is a very real issue which due to its complex, global causes, doesn’t have a quick fix solution.
Here a some of the increases the UK public face:
The majority (88%) of households in England will face a maximum increase in council tax of 4.99% which adds an average of £109 to a typical band D bill. Due to some councils facing severe financial hardship Bradford, Newham, Birmingham, Somerset, plus Windsor and Maidenhead have been granted permission to raise council tax above the current 4.99% cap.
Average energy bills are expected to rise to £1849 annually. Energy regulator Ofgem has increased the price cap for the third time, resulting in an extra £9.25 per month. Fixed-rate deals will see no change in cost until their term expires.
Water bills are expected to rise by 26%, which is £123 annually. Last March, private water firms in England reported a £1.7 billion pre-tax profit. Yet the public still endure an expensive service, regular leaks and sewage discharges into the UK waterways and coastal areas.
As of April 1st, 2025, food inflation in the UK continues to rise, with food prices overall 2.4% higher than last March. This itself was up from 2.1% in February, according to the British Retail Consortium-NIQ shop price index.
There are also scheduled increases in the cost of UK vehicle tax, TV license, mobile and broadband services and many other consumer industries.
These factors combined with the prospects of a global trade war and other geopolitical problems, mean that the economic prospects for the next financial year are far from good. The dour economic outlook makes it increasingly difficult for the UK government to rebuild the country’s crumbling public services and hamper wider plans to grow the economy. As for the public, wage stagnation coupled with the freezing of income tax thresholds until April 2028, will mean that many households will struggle financially. Shortfalls in disposable income frequently leads to daily expenditure being paid for by credit card. As of April 2024, UK households held an average of £2,487 in credit card debt, with total outstanding credit card debt reaching £70.1 billion. This is a 7.02% increase year-over-year.
Wealth and poverty can be relative things. For example, does choosing not to get into debt to finance a family holiday make you poor or just financially prudent? Can you be poor with an annual salary over £100,000 a year? As ever in life, simple or binary answers tend to be spurious and inaccurate. Nuance, complexity and context are required to reach a greater understanding. However, there comes a point when the realities of increasing monthly costs upon a household budget is no longer debateable. I do not consider my own financial situation to be dire, however the recent increases in the cost of living, especially with regard to food inflation have been clearly noticed and felt. As it is unlikely that any major changes or assistance are going to be forthcoming from the state, I suspect many of us will be looking at our own personal budgets and determining what costs can be reduced in the months to come. “Awful April” may well become a much longer affliction.
If you visit the websites for such UK tabloid newspapers as the Daily Express or the Daily Mail you will no doubt encounter prominent stories about Megan Markle, Nigel Farage and “immigrants”. If these two august institutions are short of column inches, they’ll run a piece about how some former celebrity has had the unmitigated gall and temerity to get old. I mean WTF? How dare they do what human beings are genetically disposed to do. It’s outrageous. Similarly, head over to the Unherd website and you’ll find foam flecked tirades regarding spurious points of contention over dubious subjects. Often the topic being harangued is incredibly niche and I’ve never heard of it before or even considered it being a thing. These sort of talking points are not about informing, debating and most certainly aren’t about thinking. They exist to provoke reactions.
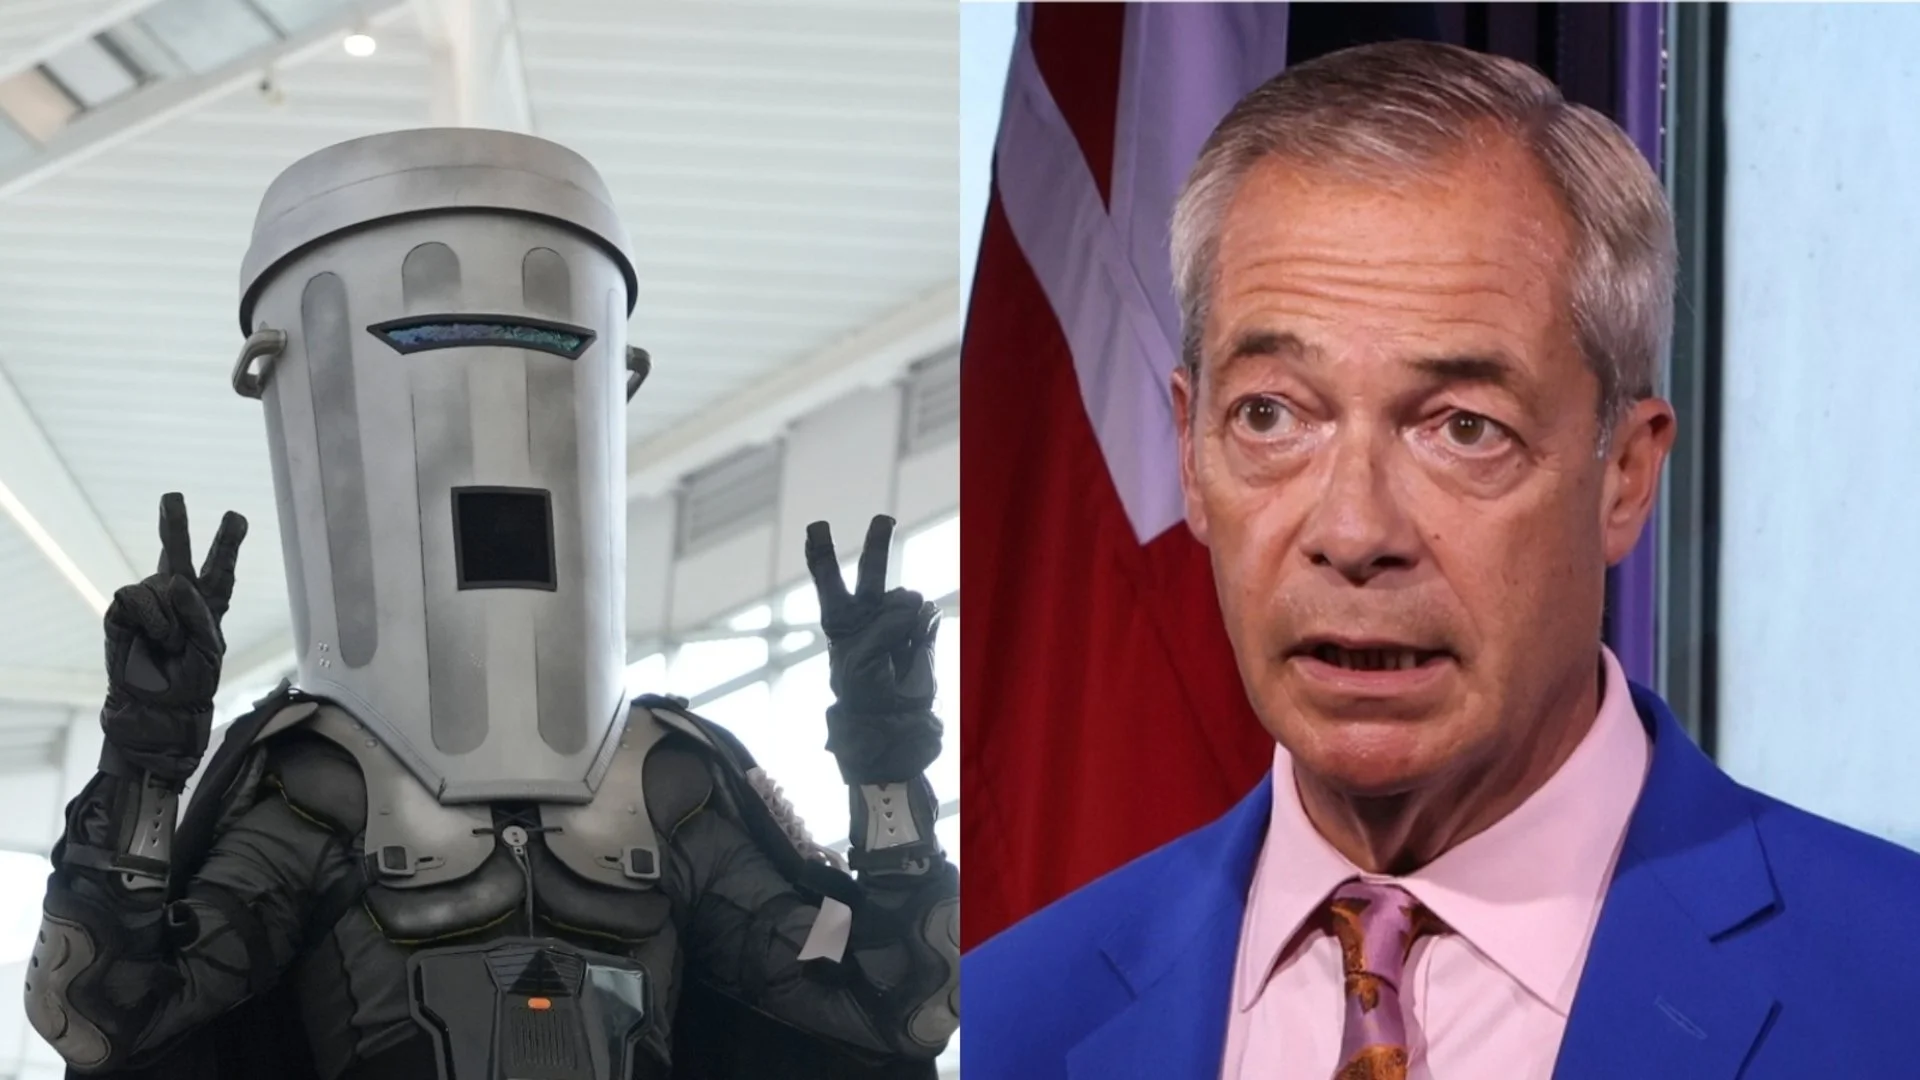
Yesterday afternoon, Nigel Farage the Member of Parliament for Clacton and leader of the Reform Party, held a press conference in which he declared that he would be resigning his seat and thus triggering a by-election. He cited the following list of grievances that have led to him making this decision. That the Parliamentary standards investigations were being politicised, the media and other parties were conducting a coordinated campaign against him and that he had endured years of threats and physical attacks. He further asserted that his family’s privacy and safety had been breached as well. He finished by alleging that the political system was repeatedly changing rules to obstruct Reform and that he was the most attacked politician in the UK. Rather than be judged by the legacy media and the “establishment”, he would rather put the issue of his political integrity to the electorate of Clacton. He even offered to pay for the cost of the by-election.
UK Prime Minister, Sir Keir Starmer has resigned and intends to leave office before the parliamentary summer recess. By then Andy Burnham will more than likely be voted leader of the Labour Party and by default will become the new Prime Minister. Due to the current size of the incumbent Government’s majority, there is no pressing reason for a General Election that the UK’s right wing tabloid press is currently calling for. Whether this provides the Government with the reset they’re hoping for when Parliament reconvenes in autumn remains to be seen. With seven Prime Ministers coming and going in a decade, there are some serious questions to be asked about the current state of UK politics. However, the mechanics of contemporary politics, the decline of clearly defined ideologies and the people that seek elected office to be our leaders are only half of the problem. The other major impediment to the UK’s democracy functioning properly is the electorate.
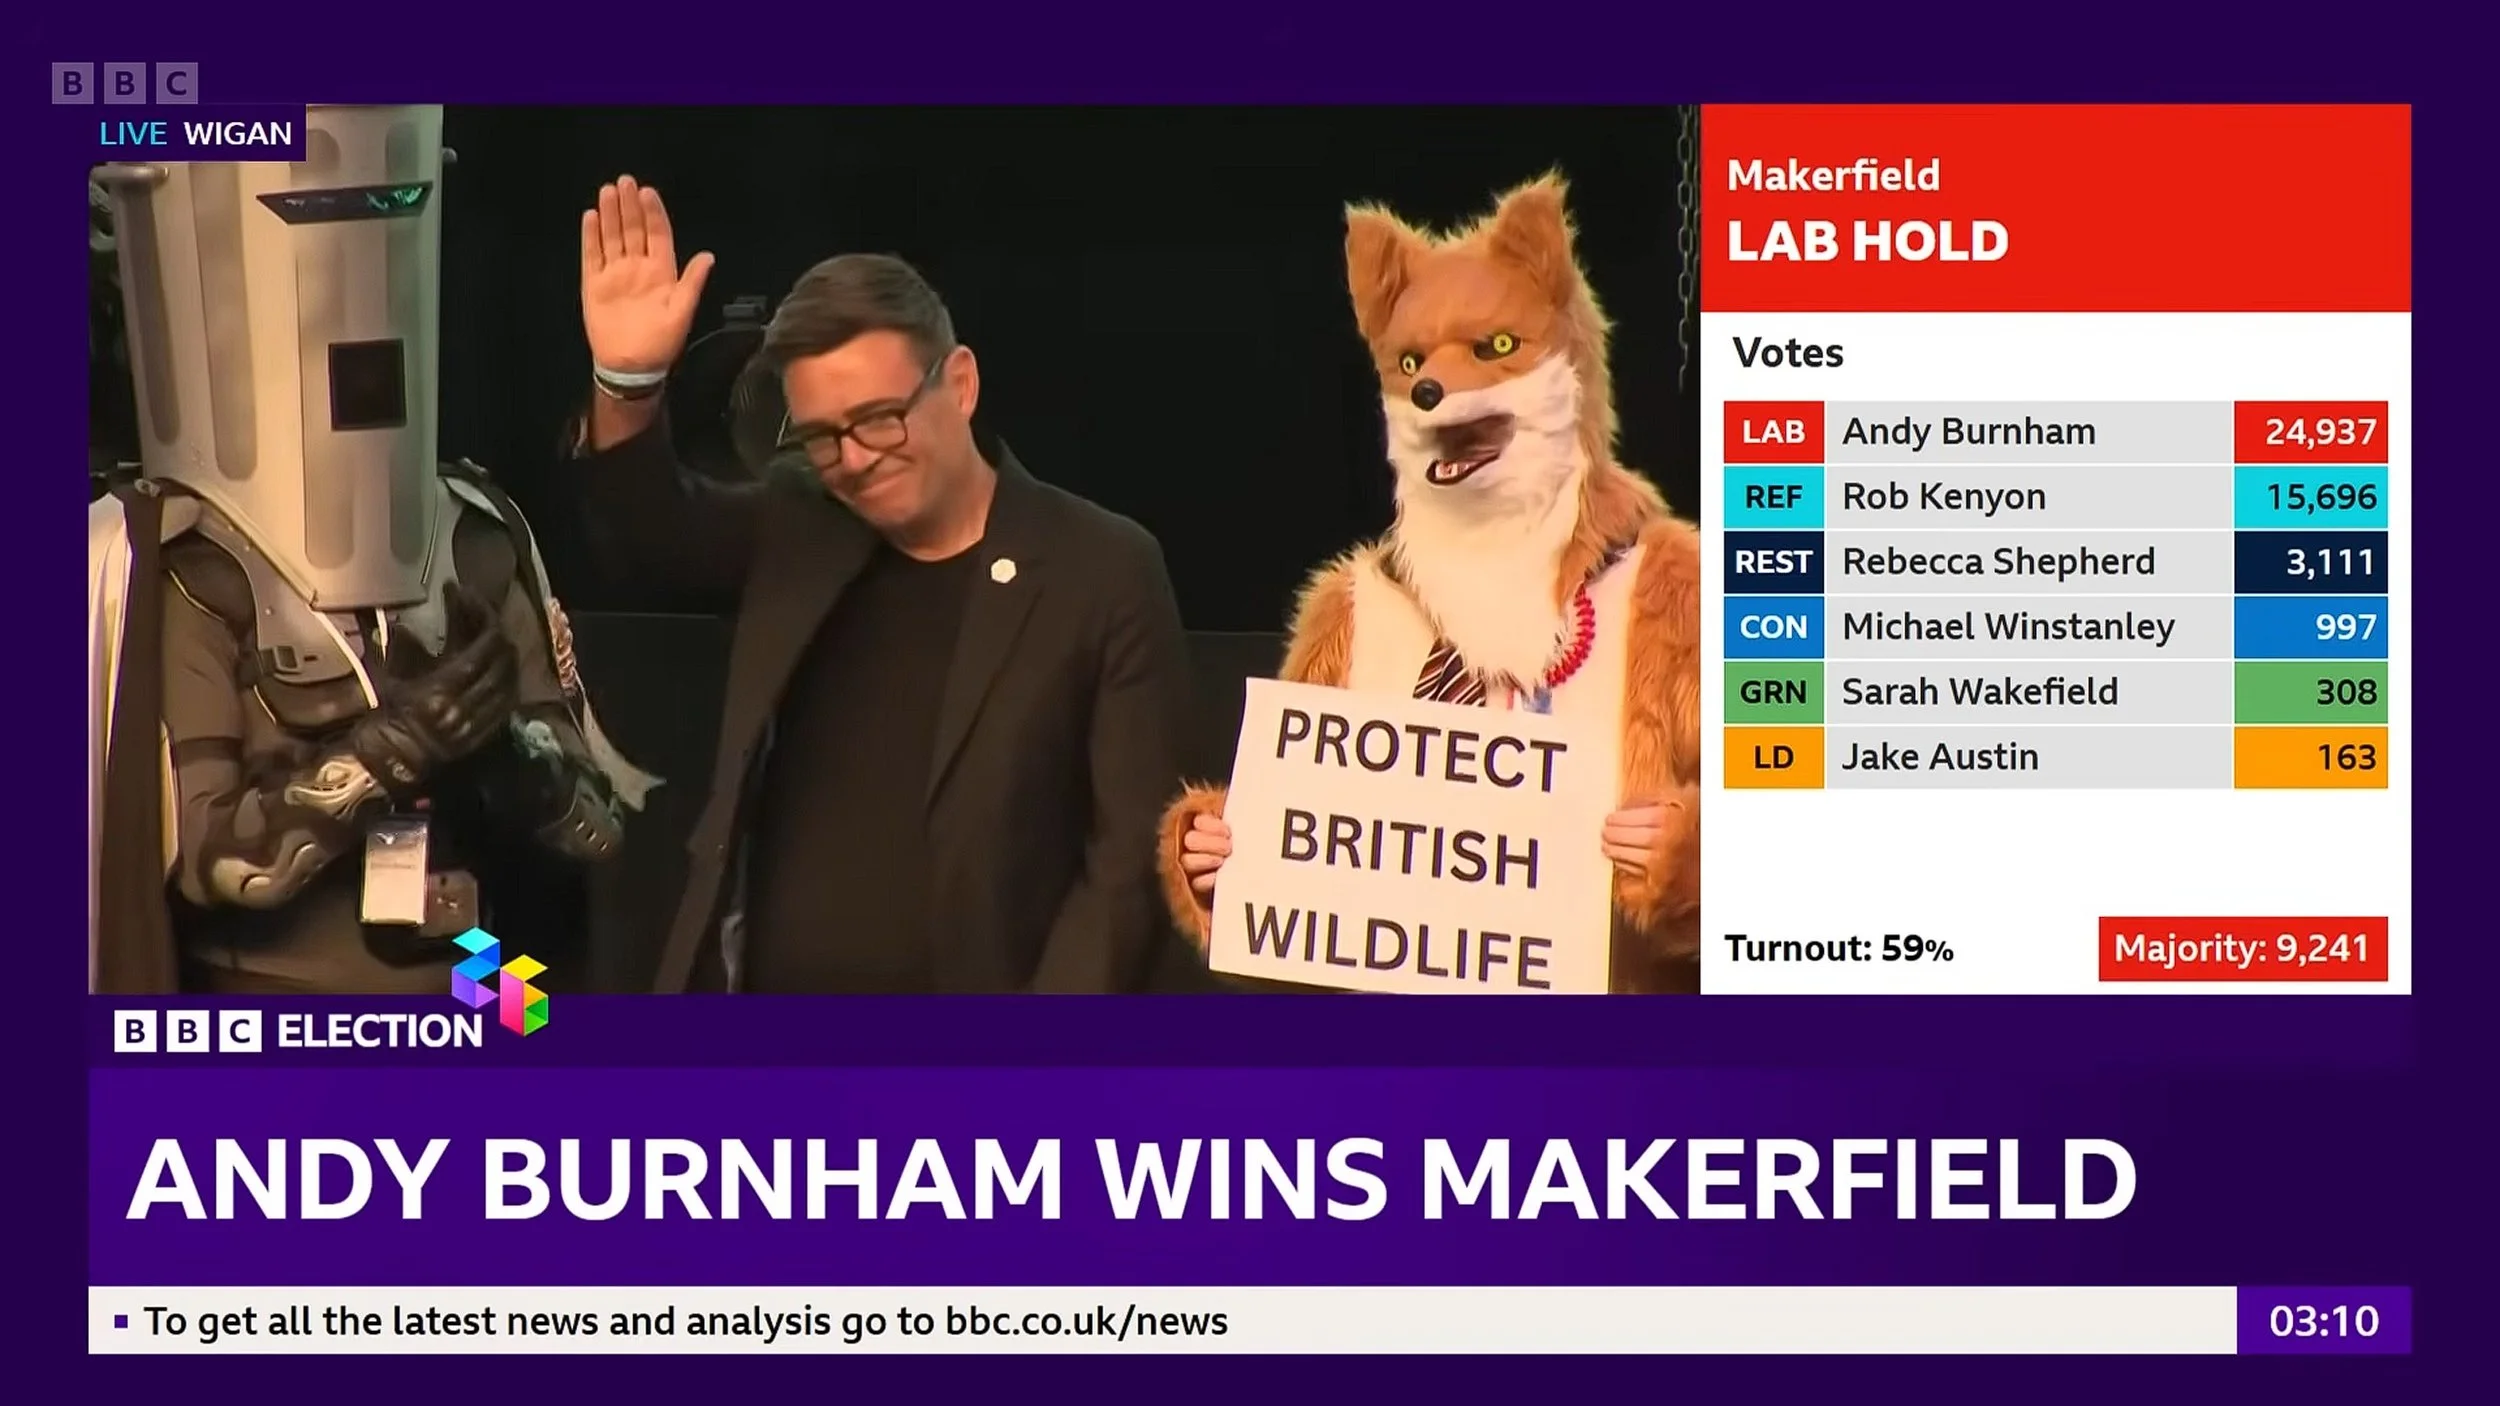
Andy Burnham successfully won the Makerfield by-election yesterday, returning him to the House of Commons as a member of Parliament after holding the position of Mayor of Manchester for the past nine years. Prior to this, Burnham was Labour MP for Leigh from 2001 and 2017. He served in both the Tony Blair and Gordon Brown administrations and has held such senior governmental posts as Chief Secretary to the Treasury, Secretary of State for Culture, Media and Sport and Secretary of State for Health. His return to Parliamentary politics is likely to result in a leadership challenge to incumbent Prime Minister Keir Starmer. When speaking after winning yesterday’s by-election Burnham spoke of “a final chance for change” the current trajectory of the present Labour Government. However, I don’t wish to focus on any of this at present. I am far more interested in the above picture, taken as the results were announced and what it says about UK politics.
The UK Government has formerly announced its intention to ban under-16s from using social media. This is due to increasing public pressure that “something must be done” about the perceived iniquities of many online platforms. However, as with most complex social problems of this nature, no one has any clear or practical ideas as to what that “something” is. It remains a nebulous, non-specific panacea and clearly someone else’s job to identify and implement. As ever, why choose a nuanced and multifaceted solution to a complex problem, when it is far easier and politically expedient to just “ban” something. The former requires effort and a degree of thinking. If such an approach fails it also means that those who came up with it now carry the can. The latter dumps the problem in the lap of various third parties, who can then be conveniently blamed when the ill conceived policy fails.
Every Thursday, Mrs P volunteers at a food bank that is run from a local church; Avery Hill Christian Fellowship. Today there was a shortage of staff so I agreed to help out. It proved to be an equitable arrangement as she collated the various orders and I packed the bags and took them to the respective clients. The food bank itself is organised and administered by the Trussell Trust, a UK based NGO and charity providing emergency food and support to people locked in poverty. It is open for 2 to 3 hours a week depending upon demand. During today’s session we served just six people. Some weeks its can be triple that amount. Upon closure, a member of staff from the Trussel Trust did a stock take and collated a list of what was needed. This is provided by various local church communities via parishioners donations, as well as local supermarkets who have an arrangement with the trust to provide surplus stock or good approaching the end of their sales window.
Under the First Past the Post electoral system, the candidate(s) receiving the highest number of votes in each constituency are elected. This system is used in the UK during general elections and in some local elections, such as those recently conducted in England. An alternative approach is the system of proportional representation, which aims to allocate seats in a manner that reflects the popularity of various parties. Both the Scottish Parliament and the Senedd in Wales employ systems of Proportional Representation. Historically, first-past-the-post has been seen as advantageous for the Conservative and Labour parties. It poses challenges for smaller parties whose votes are distributed evenly across different regions, making it difficult for them to secure seats. This dynamic effectively prevents potential competitors to the Conservatives and Labour from succeeding electorally. Consequently, due to this situation, voters may hesitate to support these smaller parties from the outset.
There are local elections being held across the UK today. Voters in Scotland and Wales will elect representatives to their respective national parliaments, while in England the voting is for local councils and regional mayors. These are the first major elections to be held in the UK since the 2024 General Election which saw the Conservative government of fourteen years, fall to the Labour Party. Midterm elections are often a litmus test for how the electorate think the national government are performing although local issues are also a major factor. The consensus among political journalists and commentators is that the incumbent government is polling extremely poorly and will subsequently face a backlash. In recent years the UK has seen a decline in traditional two party voting with Reform UK and the Greens gaining significant traction among the electorate. Hence today’s elections may well see both these parties make significant gains.
Our household is currently trying to reduce our monthly overheads in response to the ever increasing cost of living. April is not that far away and a great many service providers will increase their rates and tariff as the new financial year begins. Then there is the ongoing effects, both direct and indirect, of inflation to consider. Although the UK inflation rate is dropping, currently sitting at 3.4% in December 2025, food inflation remains higher at 4.5%. Being based in the UK, salaries and billed services tend to be administered monthly. You get paid usually at the end of the months and bills can turn up at any point, depending upon when you started a service. Any payments coming from central government, such as state pension or other benefits, are paid every 4 weeks. This means that there are 13 payments in a year. I thought it pertinent to clarify this point as other countries, such as the USA, favour a fortnightly financial cycle. Hence as a household we work around a monthly budget.
I don’t know if you have noticed that there are quite a lot of companies that have names taken from Tolkien’s Legendarium. At first glance, this seems innocuous enough. Tolkien’s writings grew in popularity over the seventies and eighties but since the release of the film trilogy at the start of the twenty-first century, his work has become more well known and been assimilated into our wider pop culture. Hence, it seems quite logical that a startup tech company, for example, would choose a name from his writings. No doubt the founders grew up reading The Lord of the Rings and are fans. That all seems plausible. However if you take a further look, it gets somewhat more complex. Here are four companies that have Tolkien based names.
“Managed decline” is a phrase that refers to the processes associated with the end of a specific lifecycle, with the goal of minimizing costs or other forms of loss. The concept originated in business where it referred to the management of companies and industries. More recently it is used in wider contexts. The concept gained prominence with regard to urban policy, particularly in the UK during the eighties when several major cities suffered economic and political collapse. Of late, the term has been applied to the UK, encompassing a systematic weakening of the economy, social structures, and cultural values, as well as its global political and diplomatic force. In each case, managed decline involves making strategic choices about resource allocation and accepting the consequences of those decisions. It is a complex issue with ethical and practical considerations, often sparking debate about the best way to address decline and reverse the process.
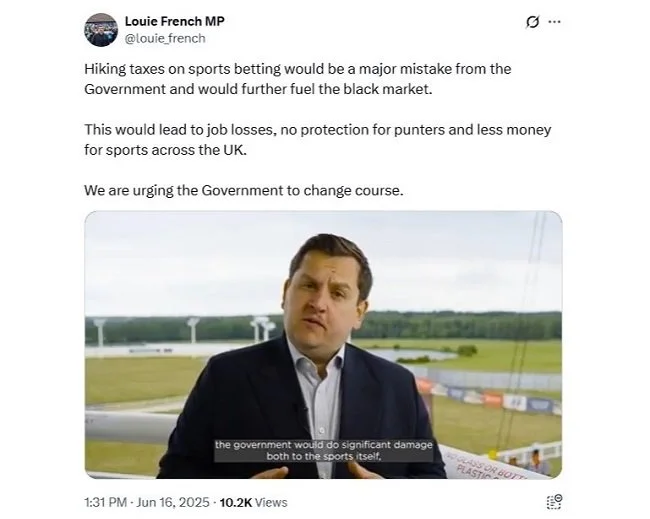
I still maintain a legacy presence on Twitter/X and I follow my local MP (member of Parliament) Louie French. It’s not something I especially relish as I am not a supporter of the Conservative party (or any other) and I did not vote for him in the last election. I just like to know what he is up to as he is the political representative for our constituency. As the Conservatives are out of power at present, to all intent and purposes, Mr French is a backbench MP although he has a minor position as Shadow Parliamentary Undersecretary (Culture, Media and Sport). However, with that being said he is hardly a key member of the shadow cabinet. Hence he focuses on constituency work and that which is generated by his shadow posting. He will also lend his voice, when required, to any major policy decision or statement made by his party.
Sunday 6th April is the start of a new financial year, here in the UK. According to data from numerous financial and economic institutions, an estimated million plus households will be facing annual increases of £400 to £500 as the proverbial “cost of living” goes up. Everything from Council Tax to Mobile and Broadband costs are being increased. Future cost hikes are expected in our energy and water utilities. As bills start going up across the country today, average wages remain stagnant. Middle-income and poorer households have been worst hit by this wage related issue. Hence the tabloid press have labelled the start of the new financial year as “Awful April”. Hyperbole aside, this is a very real issue which due to its complex, global causes, doesn’t have a quick fix solution.
I consider myself to be a grounded, rational individual. I am not excessively emotional. I like facts, data and reason as opposed to hyperbole, rhetoric and bluster. That being said, I am aware that the world is an imperfect place. Opinions are often not based upon empirical fact but personal perspective. Hence many people experience reality differently to me. They are driven by their feelings and other factors. However, despite these differences in philosophy, for most of my life the world has remained functional and over time slowly improved in subtle ways. Deference to expertise, a sense of community and basic pragmatism meant that people broadly pulled in the same direction. Of course there has always been dissent but it has been within a stable system. However, of late I feel that this era is now finally over. Things are no longer stable. We live in an uncertain world.
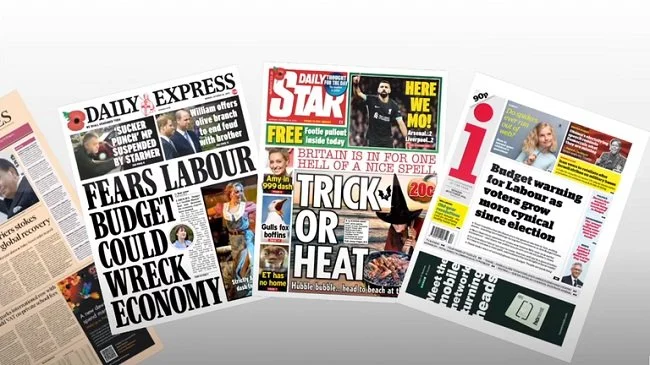
Newspapers were an integral part of UK culture in the seventies. During the week, they were delivered prior to going to work, so you would peruse them over breakfast. Alternatively you would buy one en route to your place of employment and read it on the bus or train. In a world before 24 hour, rolling news, they were the primary means of keeping the public abreast of events and as such, enjoyed a substantial audience. On occasions a newspaper story could make or break a political career or launch a crusading campaign to address a social ill. Newspapers were a force to be reckoned with and therefore a significant part of the socio-political landscape. However, due to a strong union presence within the workforce, the UKs newspapers often lagged behind other industries with regard to the technology.
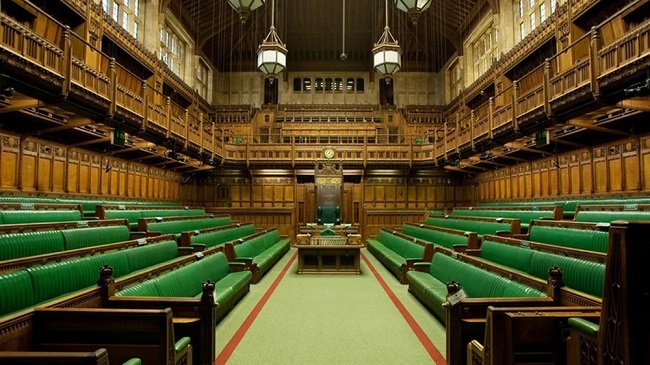
The First Past the Post (FPTP) electoral system used in the United Kingdom, as well as in several other countries such as the US and India, has both advantages and disadvantages. However, despite being a simple and straightforward system it has been abandoned by many democracies in favour of more proportional and equitable methods. The primary criticism against FPTP is that it allows a minority of the electorate to return a majority government. Since 1935, there have been majority governments 90% of the time, but not one of them had the support of a majority of voters. At present, the current UK government has a majority of seats with just 43.6% of the votes. In the 2019 election they gained an extra 48 seats despite an increase of only 1.2% of the vote share.
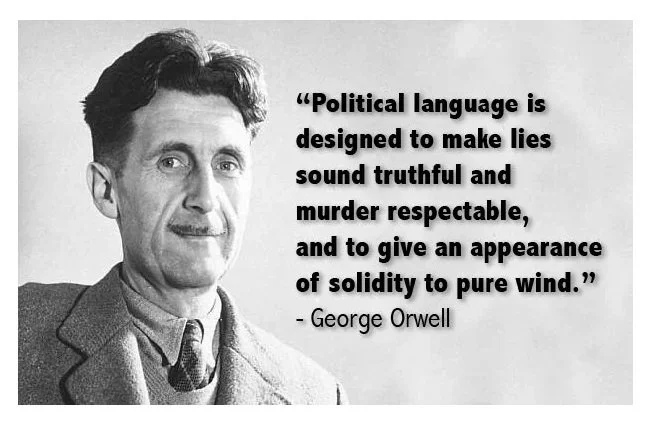
Politicians have a distinct way of talking when being interviewed or giving a press conference. It is often characterised by a strategic use of language, centred around rhetorical devices, persuasion techniques and a careful framing of messages. Direct answers to questions are usually avoided, with tangential responses being preferred. Opinions and specific perspectives are frequently presented as facts. There is also a propensity to focus on “problems” and apportioning blame, rather than “solutions”. It’s important to note that the use of language in politics is a complex and dynamic process influenced by various factors, including cultural context, media dynamics, and the evolving political landscape. Different politicians may employ different communication strategies based on their individual styles and objectives. Here are some key aspects of how politicians use language:
The United Kingdom is one of the few democratic countries in the world that does not have a single, written constitution. Others include Canada, New Zealand and Israel. To date, its constitution is a combination of written and unwritten sources, including statutes, common law, conventions and somewhat esoterically, royal prerogatives. The reason for this is predominantly historical. Since 1688, Britain has not experienced a revolution or regime change, which often leads to a constitutional initiative, such as the American or the French Revolution. Britain’s constitution has evolved slowly over time under relative stability and as such, it has never been deemed necessary to list the fundamental laws and principles of the country's political system.

On Friday 15th September the former actor and comedian turned internet social commentator, Russell Brand, released a video on his YouTube channel addressing allegations about his personal life, ahead of a forthcoming UK current affairs documentary. Brand vehemently denied what he described as “very serious criminal allegations”. The following day Channel Four broadcast “Russell Brand: In Plain Sight”. During the course of the program Brand was accused by one woman of rape and by three others of sexual assaults, and emotional abuse between 2006 and 2013. During the course of the week, further claims have been made against him and that his “predatory” behaviour was an open secret within the TV industry. Furthermore, women would warn each other in advance if they had any dealing with him. All of which has played out against a mixture of broadsheet analysis, tabloid hyperbole, performative politics and internet bluster.
For those who live outside of the UK, let me categorically state that Brexit has broken British politics. Prior to 2016, national politics still broadly functioned along traditional party political lines, with income and class substantially determining voter allegiance. The big three cities (London, Birmingham and Liverpool) maintained their liberal dispositions and Scotland, Northern Ireland and Wales were dominated by their regional politics. Brexit changed all this creating fault lines that fell outside of the existing political status quo. Opinions differed based upon where you lived, how politically literate you were and even education. Your party political allegiance no longer indicated what stance you took on this matter. Furthermore, the discourse around this complex subject was quickly debased into a bipartisan culture war that was toxic and dangerous.
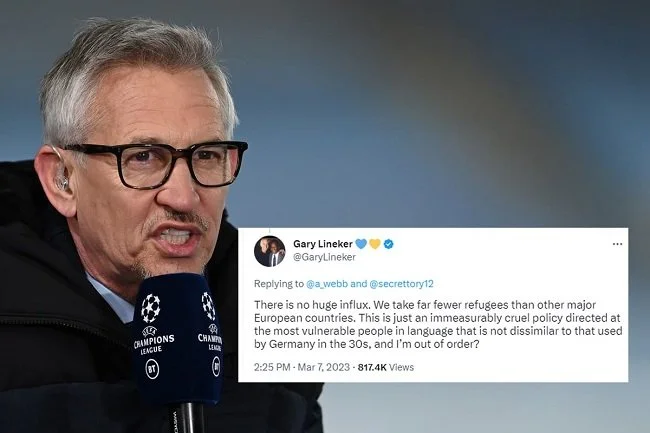
Okay, keep up as there’s a lot of ground to cover. The UK government is currently suffering in the opinion polls and after 13 years in office, is facing potential oblivion at the next general election. In an attempt to shore up support among the party faithful, the Prime Minister, Rishi Sunak, is currently pursuing a hardline with regard to immigration. According to Ipsos, as a political issue about 29% of the electorate consider immigration to be a major problem. The remainder either think current levels are manageable or have no substantive view on the matter. However, as a “culture war” issue that can be weaponized by the tabloid press, which often has direct links to the Conservative Party in the UK, immigration is a hill to die upon. Hence you will find a lot of rhetoric that is anti-immigration and any contrary view is tarred with trite pejorative terms such as “lefty”, “liberal” and “woke”.
Last April, the Election Act 2022 became law within the UK. The Act introduced a requirement for all those voting in-person to produce photo identification when attending a polling station. This is the first time that such an ID has been required. Prior to this, voters could either bring their polling card to verify their identity at the polling station, or confirm their registered address from the electoral roll with staff. Now a UK driving licence or passport are considered the primary means of identity. A list of additional photo identification that has been deemed acceptable, is available on the UK government website. For those members of the electorate who do not have any of the qualifying ID, there is a Voter Authority Certificate available, which can be applied for online. This photo ID is linked to the applicants National Insurance Number. For further impartial information on photo ID and registering to vote, visit the The Electoral Commission website.

I am writing this post from the perspective of a UK citizen, but the sentiments expressed are applicable to anyone who lives in a country where you have democratically elected local political representation. IE someone who is supposed to advocate on behalf of your community or for you personally as the duly elected political representative. Here in the UK, the country is divided into 650 constituencies, each returning one Member of Parliament. Irrespective of whether you voted for your MP or whether you support the political party that they belong to, they are obliged to represent you and advocate on your behalf, if you request it. Such is the relationship in principle between constituents and MPs in the UK. It is important to be aware that your local MP is not a delegate whose sole purpose is to represent majority constituency views. Under the UK political system, an MP makes decisions on behalf of constituents and can take a position counter to local opinion, if they feel that is in the best interest of the constituency.
It is difficult to write about the state of UK politics with any degree of intellectual rigour when the entire situation has become so utterly farcical. My initial reaction to the recent departure of Liz Truss after just 45 days in office, was to laugh with abject scorn and derision. She was destined to fail due to utter lack of ability. However, there is still the outstanding matter of the country lacking a credible and functional government to address inflation, the cost of living crisis and resolve all the issues stemming from Brexit. There are problematic national and international events taking place that need addressing. A united, pragmatic and empathetic government is required to solve both these short term and long term needs. Sadly, the governing party is riven with opposing factions and there is no commonly held policy or underlying ideology. The PM may well have changed but the underlying flaws remain.
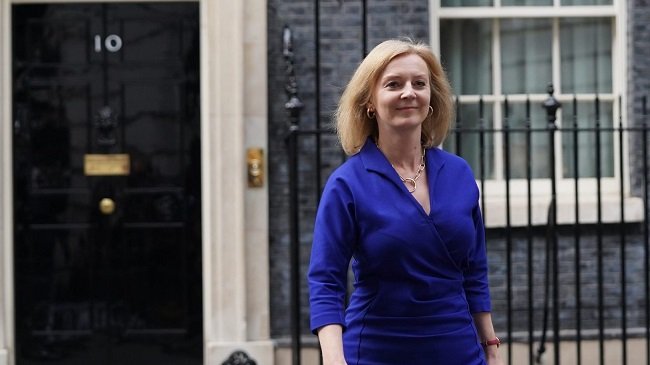
Conservative Party has been in government in the UK since 2010. During that time there have been three Prime Ministers. Today we moved onto the fourth. After Boris Johnson resigned on 7th July, the nation has had to endure a tedious two month process in which the Conservative Party elects a new leader. That person then becomes the PM by default. Many readers unfamiliar with the UK political system may be surprised that a change of leader has not led to a General Election. That is because the Conservative Party still holds a parliamentary majority of 71 elected Members of Parliament. Hence it is still constitutionally quite able to govern, despite Boris Johnson being forced from office. Therefore party members vote for a new party leader who gets the top job by default. Remember that in the UK, the Prime Minister is not the head of state and does not have the executive powers of a President.
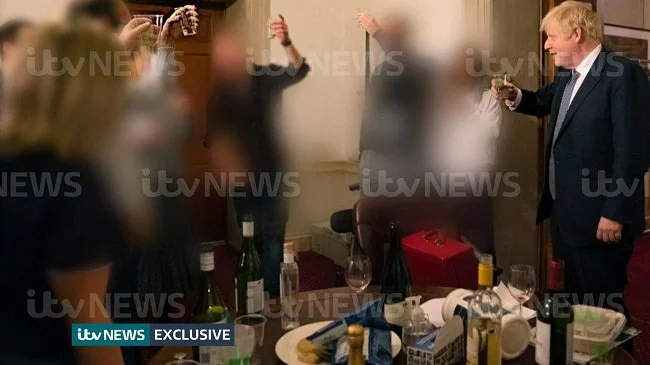
I try to keep my thoughts on political matters to a minimum here at Contains Moderate Peril, mainly because UK politics and the current state of discourse associated with it has become an absolute shit show in recent years. Brexit broke traditional politics and has made matters far more tribal and partisan. The two main parties have declined from having clear ideologies, identities and manifestos, to becoming either a lobby group for the specific demographic group that supports them, or a conflicted, divided and schizoid shadow of its former self. I’ll let you work out which is which. Politics is no longer about governing a nation for the benefit of all its citizens. Now you simply pick a side and join the ongoing culture war against everyone and everything else. This rotten system produces rotten leaders. Hence, when Alexander Boris de Pfeffel Johnson became Prime Minister in December 2019, it was clear that the nation was taking a major risk on such a man. His failings as a politician and a person are a matter of public record for anyone who has the eyes to see them.
The title for this post is a quote from The Hobbit by J.R.R. Tolkien. I’ve used it as a verbal cue to try and give readers an overview of the point I’m striving to convey. Because I want to talk about modern life in western civilization, specifically its complexity and increasing uncertainty. If you’re extremely wealthy you can mitigate these two points but I’m working on the premise that most of the people who read Contains Moderate Peril are not. The blogging community, of which I am a participant, is a diverse group but from what I’ve observed it’s not populated by millionaires. In fact most of the people I know, both online and in person, are just holding down a job, trying to keep a roof over their head and pay the bills. Often they’re doing the job they do in default of anything else and they’re at the very least ambivalent towards it. The pandemic has also brought home how fragile so-called “normality” is. Modern politics are also volatile and life in general just doesn’t seem as certain as it was twenty years ago.
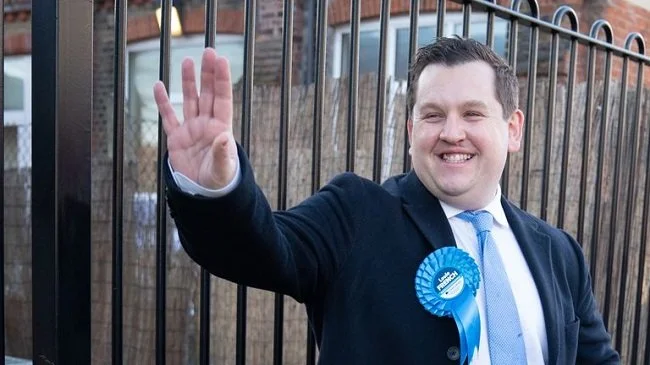
The Conservative Party successfully held onto their “safe seat” of Old Bexley and Sidcup in yesterday’s closely watched by-election. However their overall majority was reduced by more than half amid a very low voter turnout. Conservative councillor Louie French becomes the country’s newest MP after winning 11,189 votes, more than 50 per cent of those cast, in the seat previously held by the former cabinet minister James Brokenshire. Mr Brokenshire died in October from lung cancer aged 53. The closest challenger was Labour’s Daniel Francis, who secured 6,711 as the Tory majority fell from nearly 19,000 to 4,478, the equivalent of a vote share swing of 10 per cent to Labour. Turnout in the constituency was just 34%, down from the almost 70% who voted in the 2019 general election.
Political events in the constituency of Old Bexley and Sidcup have moved forward in the last few weeks, following on from the death of incumbent MP James Brokenshire on 8th of October. Although no formal announcement has yet been made regarding the date of the forthcoming by-election, the major political parties have started announcing the names of their respective candidates. There were initial concerns among some constituents that this safe Conservative Party seat may have been used as a means of parachuting in a candidate favoured by central office, rather than one determined by the local Conservative Association. Fortunately, that has not been the case. The UK Government currently enjoys a parliamentary majority of 79 seats and is therefore not in any urgent need of fast pathing further political allies.
Last week James Brokenshire, MP for the constituency of Old Bexley and Sidcup, died of lung cancer at the age of 53. He had held this parliamentary seat since 2010 and maintained a strong majority throughout the 2015, 2017 and 2019 general elections. Hence the constituency of Old Bexley and Sidcup is considered a “safe seat” for the Conservative Party. In fact it has only ever returned MPs from that party since its creation in 1983. As a result of Mr Brokenshire’s death, there will now be a by-election held in the constituency of Old Bexley and Sidcup to return a new MP to parliament. What makes this local election a little more interesting than usual, is that it will not be taking place against a wider ongoing national election. Therefore, there is scope that local issues may well play a greater part in the electioneering of all participating parties.
Before we start, let me explain to those readers outside of the UK, the significance of a Dairy Milk Freddo chocolate bar and its relevance to this post. The “Freddo” is an 18g (0.63 oz) chocolate bar, in the shape of an anthropomorphic frog. When it was re-launched by Cadbury in 1990 (it had previously been manufactured by an Australian confectionery company in the seventies), it was priced at 10p (£0.10). It remained at that price until 2005 when a 1p to 2p increase began to occur each year. By 2016 Freddos were retailing at 25p. However, the following year the price “lept” to 30p with an increase that was double its usual yearly rise. This led to public outrage across social media. Since then the price of a Freddo has waxed and waned. Tesco supermarket reduced the price back to 10p as part of their centenary celebrations. The post COVID price in 2022 hit 49p. At present, the average price of a Freddo in the UK is somewhere around 35p.